There is a financial storm coming this week, and we need to brace ourselves for it


Trading begins on the major markets after an eventful week rich in news: investors navigated between macroeconomic and geopolitical news. US President Donald Trump's statements last week about the selection of the Fed chair—particularly the fate of Kevin Hassett and Kevin Warsh's rise in the nomination race—led to more volatile trading on Friday, while concerns about the Federal Reserve's independence also intensified.
This week, commodity markets consolidated after the previous sharp decline: the price of gold was unable to remain close to record levels due to the frenzied demand for safe-haven assets after geopolitical tensions, including uncertainties related to Iran and Venezuela, appeared to ease.

Meanwhile, oil prices continued to rise as traders covered short positions and weighed supply risks, and geopolitical risks related to mass protests in Iran continued to loom over the market, while promises of potential oil surpluses from Venezuela continued to weigh heavily on expectations.

Looking back at the past week, uncertainty dominated European markets: the US-Danish relationship over Greenland, tensions surrounding Iran, and statements from Washington regarding the Fed's future direction all prompted investors to exercise caution, resulting in a wait-and-see attitude rather than a clear trend near previous highs.
Leading indices closed slightly lower in Europe on Friday, with sentiment continuing to be dominated by geopolitical risks and US political developments. The Stoxx 600 ended the day at 614.4 points, practically unchanged, the CAC 40 fell to 8259 points, the DAX 25 to 297, and the FTSE 100 to 10,235 points, while the Spanish IBEX 35 outperformed at 17,711 points (up 0.39%).

In the United States, the main indices also closed Friday with a slight decline and recorded a negative week overall. The S&P 500 ended trading at 6,940 points (-0.06%), the Dow Jones at 49,359 points (-0.17%), and the Nasdaq at 23,515 points (-0.06%).

The main drivers of the week were Donald Trump's statements and the legal proceedings initiated by the Department of Justice, which heightened concerns about the Fed's future independence, particularly given the speculation surrounding the central bank leadership ahead of the presidential transition, while geopolitical tensions over Greenland and Iran and new tariff threats also increased risk aversion.
This dual uncertainty surrounding monetary policy and geopolitical noise was enough to cause markets to shift into a corrective, wait-and-see mode on Friday, close to historic highs.
What happened on the currency markets?
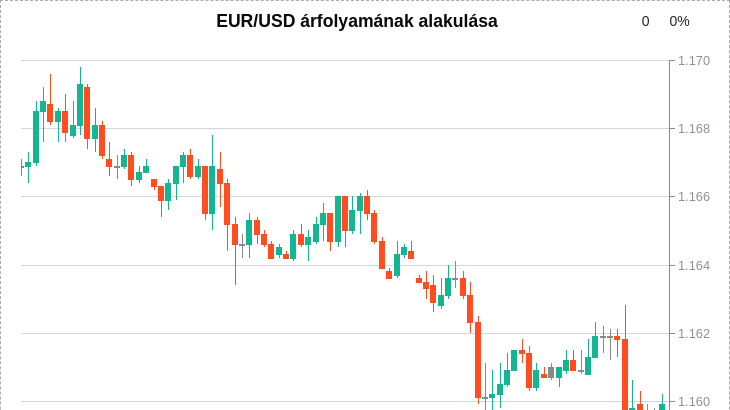
A relatively clear trend emerged on the euro-dollar market:
the EUR/USD slipped from around 1.17 at the beginning of the week to below 1.16, closing at around 1.16, which indicated a further moderate strengthening of the dollar against the euro.
The forint strengthened slightly against the euro overall during the week: the EUR/HUF gradually fell from around 386 to below 385, closing at around 384.99 on Friday evening. The movement was rather sideways, but in the second half of the week the balance shifted in favor of the forint.

The domestic currency moved within a much narrower range against the dollar: the USD/HUF typically fluctuated between 331 and 332, ending the week at around 331.9, essentially showing stagnation.

What are we going to watch out for this week?
On Monday, the National Bank of Hungary (MNB) will publish its international reserves for December. Internationally, China will release its fourth-quarter GDP figures and December industrial production and retail sales data, while the eurozone will publish its final December inflation figures. The US stock market will be closed for a holiday.
On Tuesday, the focus will shift to Germany: December producer inflation figures will be released, followed by the January ZEW economic sentiment index, which could provide important clues for assessing the economic situation in the eurozone.

On Wednesday, fresh mortgage application data will arrive from the United States, which may provide an indication of the relationship between the housing market and the interest rate environment.
On Thursday, the Hungarian Ministry of National Economy (NGM) will publish its detailed December public finance report. On the international front, the US will release its final third-quarter GDP data, latest unemployment benefit claims and November PCE inflation figures, while the eurozone will publish its January consumer confidence index.
On Friday, the Hungarian Central Statistical Office (KSH) will publish December employment data and November earnings statistics. Outside Hungary, attention will focus on January purchasing managers' indices in Germany, France, and the United States, followed by the US Michigan index at the end of the week, which will provide an insight into consumer sentiment.
Cover photo (for illustration purposes only): EU





