After the big correction, what will drive the stock markets this week?


After last week, we certainly cannot expect a dull follow-up: the markets have not even caught their breath yet, and already new impulses are arriving. The question is not whether there will be movement, but where the next wave will start.
Geopolitical noise and central bank messages continue to reverberate in the background, with US President Donald Trump capable of taking economic or foreign policy steps at any time that could cause markets to flinch, while investors search for clues in every new piece of data. A single figure can now easily bring about a shift in narrative and rearrange the balance of power.
Volatility may therefore remain, with uncertainty seen as an opportunity rather than an obstacle by the markets. The coming days may once again reveal how fragile – or how resilient – last week's dollar rally, which determined everything, really is.
Dollar shock, dollar boom
The previous week began with a rollercoaster ride on the markets: news of Japan's early elections and the presentation of the government's stimulus program increased risks, with the bond market giving the clearest signal: yields on 30-year bonds rose by 25 basis points in a single day on Prime Minister Sanae Takaichi's fiscal easing plans. At the same time, the yen began to fall.
The turmoil in the bond and currency markets prompted an immediate response from the Bank of Japan: Governor Kazuo Ueda indicated that the institution would intervene by purchasing government bonds if necessary. Meanwhile, according to market reports, the Japanese Ministry of Finance conducted a "rate check" on the currency market, which is a typical precursor to direct intervention.
The events in Japan not only shook the local bond market, but also triggered an international realignment: investors partially closed their dollar positions, which contributed to the technical break of the greenback. The movement of the yen thus became an indicator of global risk appetite.

This was compounded by uncertainty in the US regarding the independence of the Federal Reserve. President Donald Trump once again criticized Fed Chairman Jerome Powell, but the central bank did not back down. Maintaining the current interest rate sends the message that the Fed is in no hurry to ease further, while inflation may remain above target.
The central bank has limited room for manoeuvre: it has to deal with the weakening dollar, rising yields and political pressure all at once, so every nuance in its communication is immediately reflected in exchange rates.
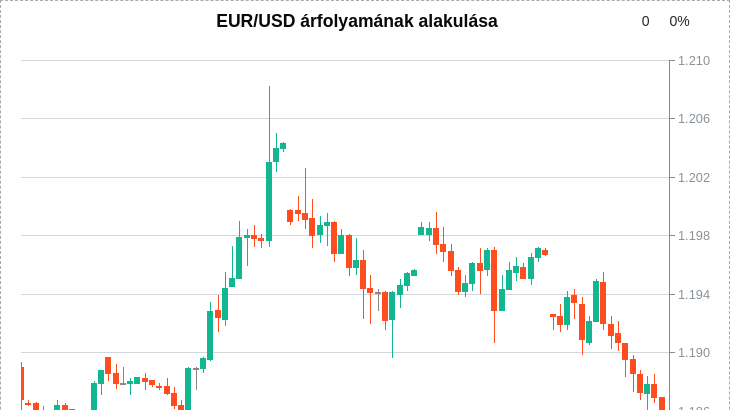
The big loser at the beginning of the week was the dollar, which was dragged down by the situation in Japan. The EUR/USD was already close to 1.20 at the beginning of the market rollercoaster, then turned into a sharp correction and fell back to around 1.185 by Friday.
Overall, the week was characterized by volatile but direction-seeking trading. The 1.20 level has proven to be strong resistance for now, but the question is how long the sudden strength of the dollar will last.
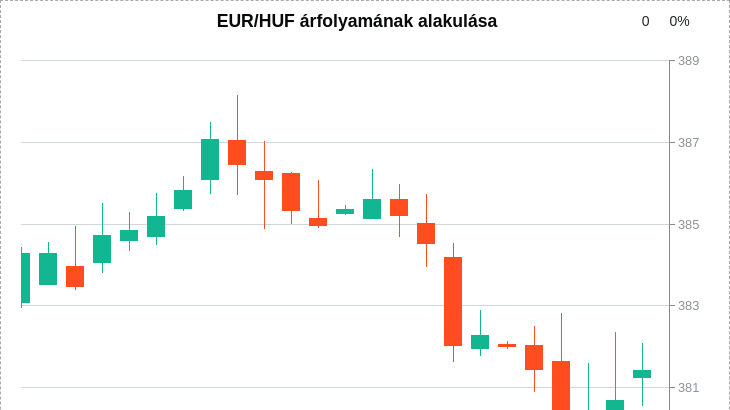
After significant fluctuations, the euro-forint exchange rate appeared to stabilize: in the middle of the week, the rate fell below 380, then corrected and closed at around 381.4. Overall, the forint strengthened slightly against the euro compared to the beginning of the year, but the movement was more volatile than trend-like.
The dynamics were more spectacular in the case of USD/HUF: parallel to the weakening of the dollar, the exchange rate fell to close to 316, which was a more than four-year high, followed by a sharp rebound in the second half of the week, closing at around 321.8.
The global correction of the dollar and uncertainty surrounding the Fed also led to rapid changes in direction here, with the forint showing greater fluctuations against the dollar than against the euro.

Stock markets and precious metals also took a beating over the week
The Budapest Stock Exchange closed a particularly strong week:
on Friday, the BUX rose to a new historic high of 128,831 points, up 0.74% on the day.
The rally was mainly supported by individual company news: OTP was boosted by several target price increases, Richter responded to a favorable European Medicines Agency opinion with a rise, while Mol and Magyar Telekom also closed higher. Trading volume was substantial, and the broad rise in blue chips indicated that the domestic market proved resilient to international volatility, even despite the dollar shock in the middle of the week.

Among the leading indices in Europe, the EuroStoxx 600 closed at 611 points, the DAX at 24,539 points, the CAC 40 at 8,127 points, and the FTSE 100 at 10,224 points, all ended Friday with a nice rise, but with a noticeable drop for the week and month.
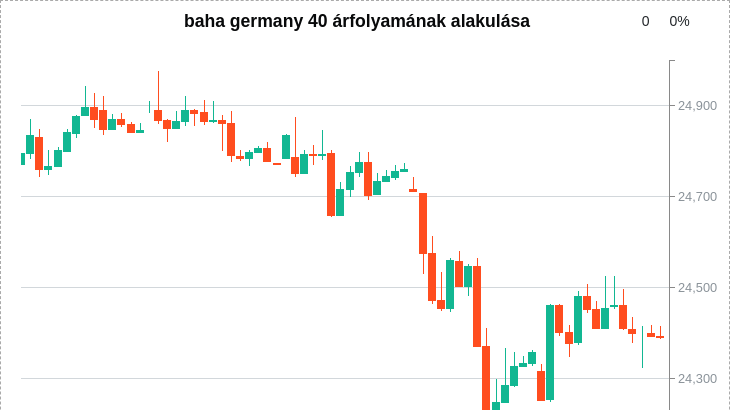
European markets were partly driven by corporate flash reports – strong figures from Adidas and CaixaBank created a particularly positive mood – while geopolitical news (Ukraine, Iran, Chinese-British relations) remained in the background.
Then, in the middle of the week, the sudden weakening and strengthening of the dollar shook the markets, triggering temporary risk aversion, but the nomination of Kevin Warsh to head the Fed ultimately reassured investors, as the market priced in the preservation of central bank independence and more predictable monetary policy.
The end of the week was weaker in the United States: the S&P 500 closed at 6,939 points, down 0.43%, the Dow Jones at 48,892 points, down 0.36%, and the Nasdaq at 23,462 points, down almost 1% on Friday, with the technology sector in particular remaining under pressure.

Overall, the month remained positive, but trading was heavily influenced by uncertainty surrounding the Fed chair and the sudden weakening of the dollar, followed by its recovery on Thursday and Friday.
Although the nomination of former Fed monetary policy committee member Kevin Warsh initially elicited mixed reactions, markets ultimately concluded that his experience and previous central bank background could be a stabilizing factor, which mitigated concerns about independence.
However, the precious metals market saw a brutal correction on Friday, with gold falling nearly 9% and silver falling about 28% in a single day.
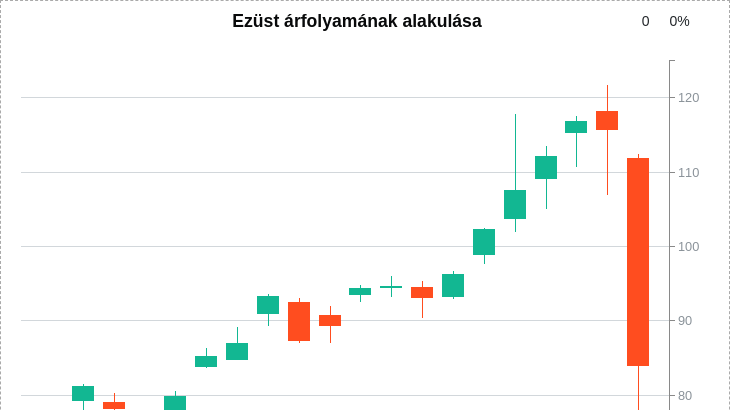
Following last month's speculative rally, profit-taking has run rampant, especially in the case of silver, where forced liquidations have exacerbated the decline due to leveraged positions and retail speculation.
This was partly responsible for the strengthening of the dollar, which, together with the stabilization of yields, also contributed to the sudden outflow of capital from precious metals, which had previously been considered "hot money."
What will we be watching this week?
The week kicks off in Asia on Monday: China releases its January manufacturing purchasing managers' index, Europe releases German retail data, and in the US, the January manufacturing PMI and ISM index provide guidance on industrial activity.
On Tuesday, the National Bank of Hungary (MNB) will publish the consolidated balance sheets of credit institutions for December, while on the international front, the focus will be on France's January inflation data.
On Wednesday, the eurozone's January inflation figure may be the most important European data, while in the United States, mortgage applications, ADP employment data, and the ISM services index may provide insight into the momentum of the US economy.
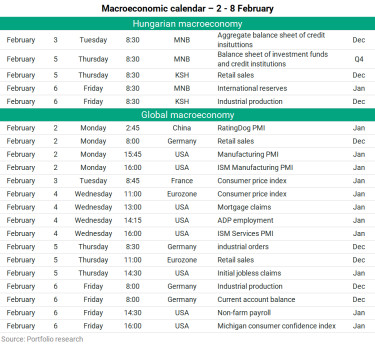
On Thursday, the MNB will publish the fourth-quarter balance sheets of investment funds and insurance companies, while the KSH will release December retail data. Abroad, German industrial orders, eurozone retail data, and US unemployment claims will be released.
On Friday, the Hungarian Central Statistical Office (KSH) will publish December's industrial data, while the MNB will publish January's international reserves. At the international level, in addition to German industrial production and the current account balance, the US January labor market report—non-farm employment and the unemployment rate—may be the highlight of the week, which will be closed by the Michigan index with its report on consumer sentiment.
Cover photo (for illustration purposes only): Getty Images





