Insurance premiums have surged in Hungary, but insurers are still making losses


The National Bank of Hungary (MNB) has published the statistics for the first three quarters of 2023 for the Hungarian insurance sector on Monday. In terms of premium income, the period from the beginning of July to the end of September was particularly good:
premium income was boosted by the "campaign" linked to the introduction of the social contribution tax on the life side and by the indexation of premiums on the non-life side.
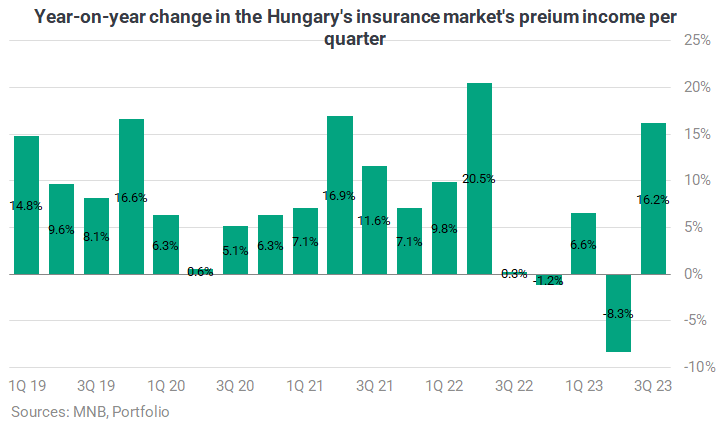
The supervisory statistics revealed that
- premium income in the life insurance market grew by 11.8% in the third quarter, but has fallen by 9.7% so far this year due to a decline in one-off premiums;
- premium income in the non-life insurance market increased by 18.9% in the third quarter, but only by 14.5% in the first nine months;
- premium income in the Hungarian insurance market as a whole grew by 16.2% in Q3, compared with only 4.1% growth in Jan-Sept.
The share of life insurance in the market is steadily declining: 63% of the HUF 1,149 billion in premium income realised by the end of September came from property and liability insurance.
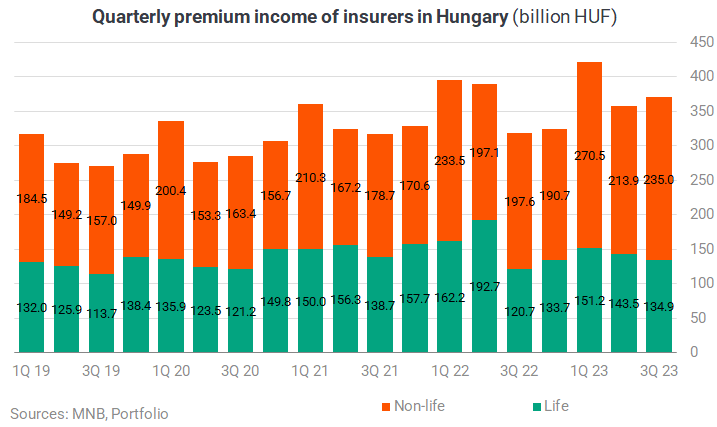
In the table below we have summarised how each product has performed so far this year. Life insurance is clearly being driven upwards by tax-advantaged pension insurance (with a slowing growth of 8% over a year to 477,000 policies), while non-life insurance is growing almost across the board, largely due to an increase in average premiums rather than the number of policies.
| Year-on-year change in premium income by product in 2023 | ||
| Cumulated 2023 | Q3 | |
| Pension | 17.2% | 17.8% |
| Unit-linked (non-pension) | -7.1% | -2.0% |
| Mixed (non-pension) | -43.7% | 76.8% |
| Risk and life | -11.3% | 15.0% |
| Third-party motor vehicle liability (KGFB) | 10.6% | 16.8% |
| Casco | 20.5% | 22.1% |
| Home | 14.7% | 16.6% |
| Non-vehicle, non-home | 15.5% | 20.9% |
| Total | 4.1% | 16.2% |
| Sources: MNB, Portfolio | ||
The life insurance market has been given impetus by the introduction of the 13% social contribution tax on savings in the summer, partly by the last-minute sales of life insurance policies taken out in June, and partly by the fact that long-term life insurance policies are not affected by the new tax, i.e. single-premium policies are exempted after 5 years and regular-premium policies after 10 years. Meanwhile, the importance of regular-premium products has increased this year, as the profit content of a significant proportion of single-premium policies has been largely eroded by the windfall tax introduced last year.
Income from regular premiums rose by 11.9% in the third quarter and by 10.3% in the first three quarters, which is apparently not a bad performance, but below the average inflation rate for the periods. Although ad hoc payments, which have had strong quarters during the epidemic, were 15% higher in the third quarter than a year earlier, the year-on-year decline is still significant at 14%. Premium income from single-premium life insurance fell 57% this year for the reasons mentioned above, but was up 22% in the third quarter from last year's low base.

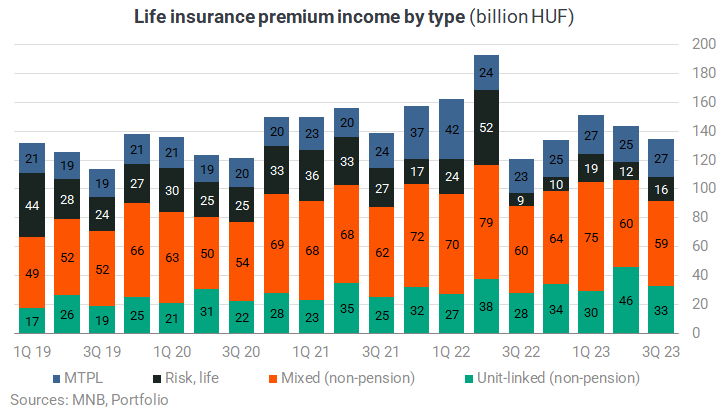
Looking at life insurance by product type, it is clear that tax-advantaged pension insurance remains teh engine of the market. Mixed life insurance also saw a surge in the third quarter, but this is exclusively due to single premium products. Non-pension unit-linked products saw a decline, with premium income from term and other life insurance growing at a rate broadly in line with inflation after a weaker performance in previous quarters.
In non-life insurance, we see a significant rise in casco (casualty and collision) and business property and liability, but the third quarter also saw a major uptick in premiums for motor third partly liability (MTPL) and home insurance, both up by 17%, a good part of which may be the result of indexation of premiums, as the number of contracts increased by 0.5% for MTPL and decreased by 0.4% for home insurance, with the number of renewals not significant for either product.
For the housing insurance market, which has 3.3 million policies, March 2024 could be the watershed date: market estimates suggest that the extra cancellation option and the home insurance campaign built on it should produce at least 100,000 contract (insurer) changes.

The performance of property insurance is strongly affected by the evolution of claims. Last summer, insurers were hit by drought damage amounting to more than HUF 40 billion, and this year by storm damage amounting to HUF 13 billion in home insurance alone (between 1 May and 31 August). Although these two figures would justify a decrease in insurers' claims expenditure, net claims expenditure actually increased, by 14%, or HUF 3.7 billion, for compulsory vehicle liability insurance alone, presumably due to claims inflation.
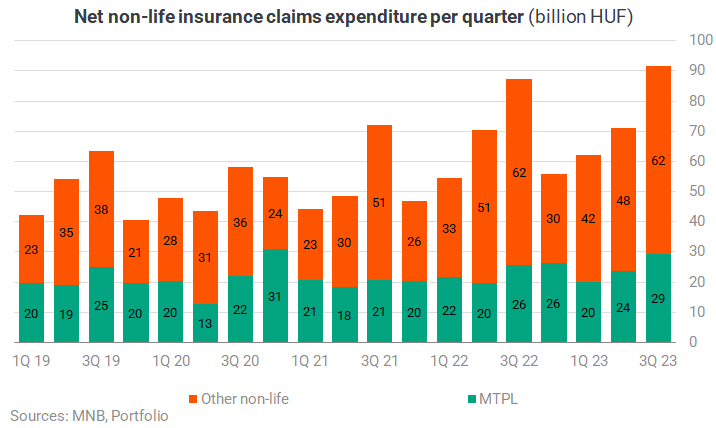
The losses concentrated in the summer are the main reason why the third quarter was the worst for insurers in the non-life insurance sector, with a negative technical result of HUF 7 billion, while life insurance recorded a gain of HUF 8 billion.
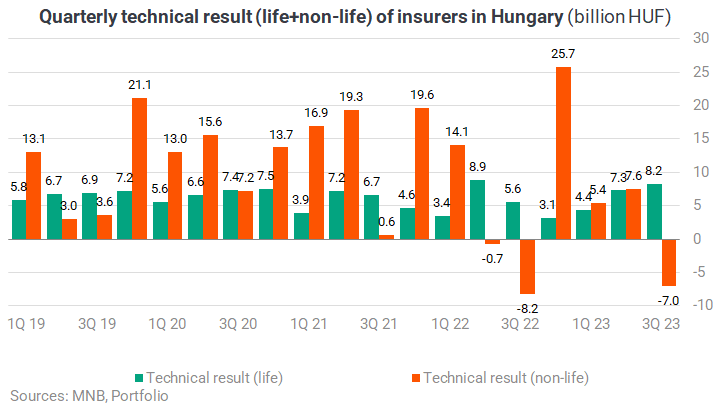
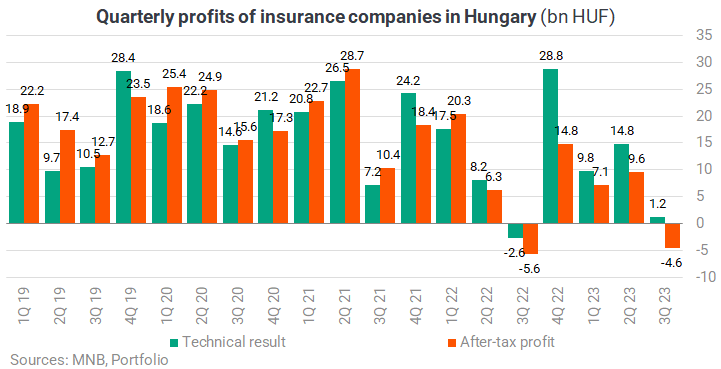
However, as insurers recorded a negative result of HUF 6 billion under non-technical accounts, the sector as a whole slipped into the red for the third quarter: the three-month net after-tax profit was HUF -4.6 billion, which means that the sector is still only at a profit of HUF 12 billion this year, which is barely 1% of premium income.
The premium income of the Hungarian insurance sector is expected to reach some HUF 1,500 billion this year, on which the Association of Hungarian Insurance Companies (MABISZ) estimates that
insurers will have to pay HUF 142 billion in "traditional" insurance tax and HUF 94 billion in extra profit tax (compared to HUF 115 billion and HUF 55 billion respectively last year).
Contrary to preliminary indications from the government, the two types of special tax are expected to remain in place next year, although insurers want to obtain a similar relief to banks in return for buying government bonds in the case of the windfall tax.
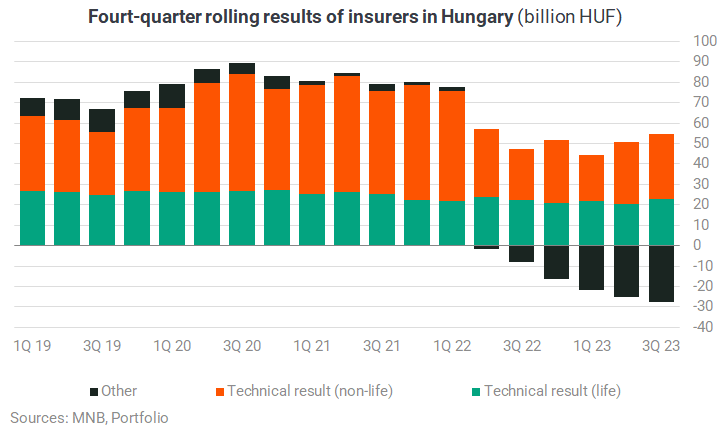
In any case, the above figures show that insurers make a profit of 1 forint on every 100 forints of premium income, while paying 16 forints to the budget in the form of a special tax. Ceteris paribus,
without the two special taxes, the sector's return on capital would be over 30%, and without the extra profit tax alone, over 10% for this year, compared with only 3-4% at best.
Cover photo: Getty Images