Hungary central banker addresses record weak forint


Central bank concerned...
Virág's comments come on the back of EUR/HUF hitting 416, weakening 4% yesterday. Agains the US dollar the Hungarian currency was quoted as weak as 410.
Virág's remark shows the central bank will not be just an onlooker of the forint's extreme weakening, but will try to put a stop to it by raising its one-week deposit (benchmark) rate considierably on thursday.
The Deputy Governor's words helped the forint recover from its all-time low to under 410.
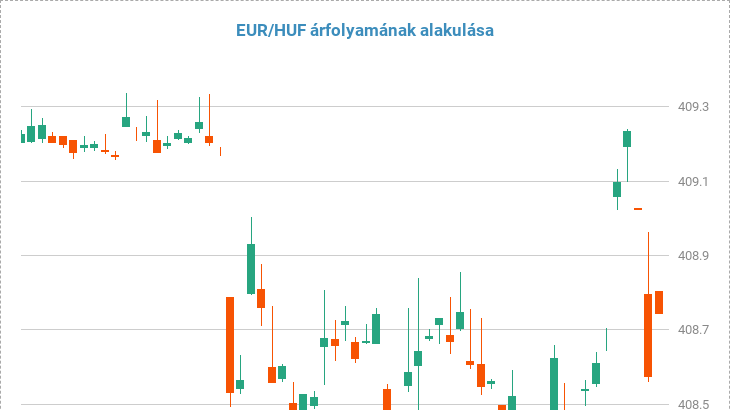
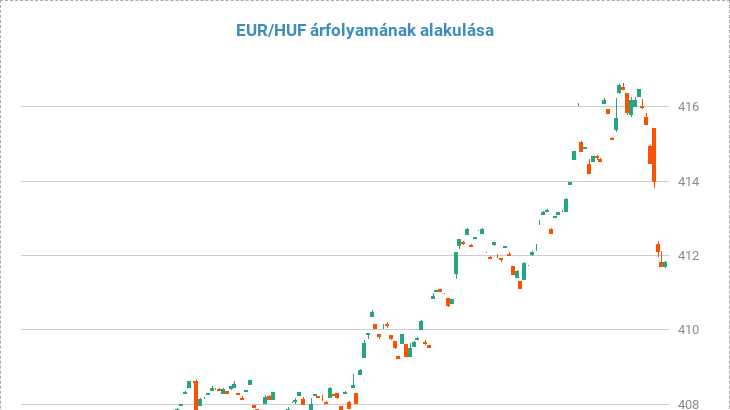
The MNB therefore intends to give a decisive response to the forint's plunge. It is worth emphasising that monetary policy is not the reason for the forint's current low, but rather Hungary's vulnerability, which is linked to the high current account deficit (due to high energy prices) and the long-standing dispute with the EU, which is preventing EU funds from flowing into Hungary. (Hungary has not reached an agreement with Brussels on the recovery fund.) On top of all this, the government has imposed special taxes (which previously led to massive HUF easing), which has delivered a blow to the business climate, and has introduced governing by decree, which has also failed to impress investors.
The underlying problem is beyond the scope of monetary policy, but the MNB is trying to ease tensions by raising interest rates, although last week's rate hike proved to bring only a temporary relief. It is a big question to what extent the MNB is able and willing to raise interest rates further, given the need to fight inflation (a weak forint is creating an even more serious inflation problem), but high interest rates are increasingly leading to slower economic growth. It is therefore clear that the real economic sacrifices are becoming ever greater, while there is no positive news on the ongoing dispute between the government and the EU to reassure investors.
Government cool as a cucumber
The war and the Brussels[-imposed] sanctions are bringing economic crisis, wartime inflation, price rises and uncertainty to the whole of Europe. Only peace can end wartime inflation. That is why the government is pushing for a peace settlement and to avoid new sanctions from Brussels that would harm Europe,
this was the response by the Finance Ministry to the questions by news portal Telex on how it would comment the extreme forint weakness.
If these words sound familiar to you, it's not a coincidence. These are literally the three sentences that government spokeswoman Alexandra Szentkirályi, in charge of communications, posted on her official Facebook page on Wednesday morning. In other words, what happened is that journalists' questions about the forint exchange rate are answered from the government's communications centre.
The content of the answer is that the government sees external causes (the Russia-Ukraine war, the new economic situation caused by the war, and the energy crisis) behind the depreciation of the forint, which suggests that the government cannot counteract these. We have already noted yesterday how oddly nonchalant the government is about the record weak forint, while the central bank has decided to act.
This approach suggests that the government has staked everything on a peace scenario, and the scenario that emerges is one in which the government - since there is little it can do in this situation - does not intend to intervene decisively on behalf of the forint.
Therefore, it will be interesting to see and hear what message, if any, minister Gergely Gulyás will convey on the forint exchange rate at a press conference today, and how it will be received by market participants.
Indeed, if there are no strong messages in favour of the forint at today's event, markets may interpret this as a sign that the government is not bothered by the record weak forint and does not intend to intervene. This could even be interpreted as the government not wishing to counter the weakening forint's trajectory determined by the new economic fundamentals (rising energy import bill, surging current account deficit, mounting foreign trade deficit, followed by forced adjustment and economic shock therapy).