What will happen in Hungary after its "whatever it takes" moment?


26 July, 2012 is a notable day in the history books of the eurozone, when Mario Draghi delivered what has since become a catchphrase at an investment conference in London:
Within our mandate, the ECB is ready to do whatever it takes to preserve the euro. And believe me, it will be enough.
The backdrop to the speech was that the debt crisis and falling bond yields had investors increasingly worried about the future of the euro area. The ECB President's words then suddenly turned the tide, with yields falling after the market believed the ECB was ready to defend the euro.
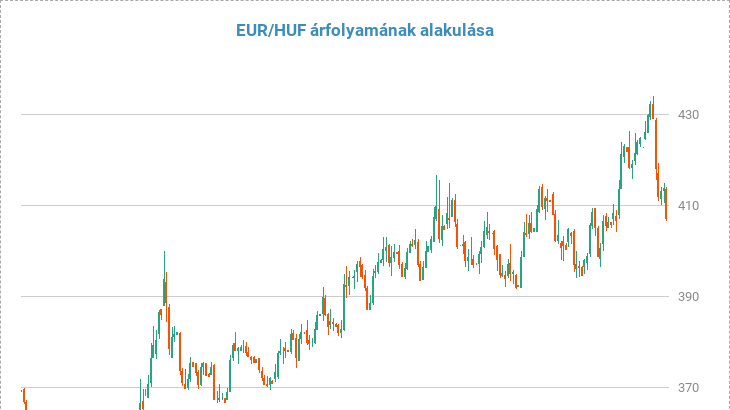
In many respects, the situation was similar in Hungary last week: the forint got into an apparently unstoppable downward spiral, bond yields were on the rise, the need to exchange euros due to high energy import tariffs kept the forint under constant sell-off pressure, while the central bank's foreign exchange reserves were sufficient but not ample. Moreover, inflation already exceeded 20% in September, while the MNB ended its cycle of interest rate hikes in late September.
Seeing the ailing of the HUF, one had the feeling that
IT IS ONLY A MATTER OF TIME BEFORE THE MOMENT COMES WHEN SOMEONE HAS TO STAND UP AND ADMIT THAT WE WILL DO everything in our power, WHATEVER IT TAKES TO PROTECT THE FORINT.
That moment arrived on Friday morning when MNB Deputy Governor Barnabás Virág disclosed the Monetary Council's decisions taken on the preceding day. This was his 'whatever it takes' remark:
In the current turbulent financial market environment, the MNB's primary task, alongside its price stability objective, is to ensure market stability. The MNB is ready to intervene with all elements of its toolbox to ensure market stability.
This practically means that the MNB has discarded the "the central bank has no exchange rate target" argument of recent years and has openly stated that its primary task is no longer just to bring down inflation, but also to ensure the stability of the forint.
Of course, the two are related, as it was precisely the uncontrolled weakening of the forint that put the inflation target in jeopardy. The fact that the central bank is openly acting to protect the forint is not necessarily entirely new either, as it has already referred to "financial market turbulence" several times in its interest rate policy in the past, but this is by far the strongest move to do so.
Given the backdrop of the announcement, it is clear that there must have been a great deal of concern at the central bank, as the Deputy Governor was reporting straight from Washington, DC, from the IMF's annual general meeting. The background briefing was scheduled to take place at 8.30 a.m. local time, which was 2.30 a.m. in Washington. However, due to technical difficulties, the details were made available only some time later, but
WHEN ONE OF THE TOP MEN OF A COUNTRY'S CENTRAL BANK IS READY TO GO LIVE AT DAWN FROM THE OTHER SIDE OF THE WORLD, IT REALLY DOES SUGGEST THAT THERE IS TROUBLE.
And there was trouble in abundance, indeed. The MNB's actions confirmed the view that the brakes had been applied on the verge of a current account crisis and an exchange rate crisis. The market welcomed the news as the forint strengthened significantly, but the question is of course how long the effect will last, whether investors have been convinced that the forint's place is firmly in a range below the 430-440 band it was hovering in last week.
In the period ahead, the optimistic scenario might be if the forint can maintain the strength it has gathered in recent days and then appreciate further by the end of the year on the back of agreement with the European Commission on the unblocking of EU funds.
The other, pessimistic scenario is that the central bank's manoeuvring keeps the market convinced only for so long, and lacking further measures the Hungarian currency will be targeted again. After that, if the talks with the EU executive fail to yield the desired results, the forint could come under renewed pressure, and the rate could even return to its previous low north of 430 to the euro.
If the second scenario materialises, we will be back to where we were before, with the difference that the MNB's foreign exchange reserves will be reduced and the central bank will have even fewer tools to intervene to prop up the huf.
By raising interest rates, the central bank has deterred speculators, and by intervening on the foreign exchange market, it has positively altered the supply and demand conditions on the forint market. Both actions were powerful and effective in the short term, but neither seems reassuringly sustainable in the longer term (beyond the end of the year). So there is work to be done, and not just at the central bank.
Cover photo: Getty Images





