U.S. could avoid a recession in 2023, but Europe may not be so lucky


GROWTH
As the remaining epicentre of global volatility, CEEMEA faces a challenging period ahead. The global environment is unsupportive, now even more so given the dual headwinds of tightening monetary conditions and a European recession,
said Morgan Stanley in its 2023 CEEMEA Economics Outlook on Monday.
Morgan Stanley expects global growth to slow to 2.2% year on year in 2023 with growth in CEEMEA barely positive at 0.1% yr/yr following a 0.6% yr/yr contraction in 2022:
Our first cut at 2024 points towards a rebound of 2.4% yr/yr. We assume that the Russian invasion of Ukraine continues, western sanctions are reinforced, and trade, particularly in energy, is erratic. We see Russia in recession throughout 2023, with Ukraine facing a shallow 2.2% yr/yr recovery next year.
"Risks are to the downside," the reports said, projecting the global economy to grow by 2.2% next year, lower than the International Monetary Fund's latest 2.7% growth estimate.
MS expects consensus estimates to fall further in South Africa, as the long tail of high inflation, tightening monetary policy and weak global growth sets in. In Turkey, they see growth slowing in 2023 even in the absence of policy normalisation, or as a response to it provided that there is a return to orthodoxy post-elections.
Finally in CE3, Morgan Stanley sees the Czech Republic and Hungary facing the biggest growth headwinds given their dual trade exposure to the EU and the global capital goods trade. For Poland's more closed economy the fiscal expansion is growth supportive.
The U.S. economy just skirts recession in 2023, but the landing doesn't feel so soft as job growth slows meaningfully and the unemployment rate continues to rise,
Reuters cited the report, which projects a 0.5% expansion next year.
"The cumulative effect of tight policy in 2023 spills over into 2024, resulting in two very weak years," the report added.
Next year, Morgan Stanley predicts a sharp split between developed economies "in or near recession" while emerging economies "recover modestly" but said an overall global pickup would likely remain elusive. China's economy was predicted to grow 5% in 2023, outpacing the average 3.7% growth expected for emerging markets, while the average growth in the Group of 10 developed countries was forecast at just 0.3%.
INFLATION
Morgan Stanley's inflation forecasts are generally above consensus, particularly in CE3, Turkey and Ukraine: In each case, they believe high wage growth and higher FX pass-through pose upside risks.
Having said that, Czech inflation should decelerate at a faster pace than in Hungary and Poland, where we see core CPI remaining sticky. Our base case for Turkey is that of a long muddle-through but our bull case involves the possibility of faster disinflation conditional on monetary tightening post-elections. South African CPI prospects are improving, but could look a lot better on a China reopening or early end to the Fed cycle.
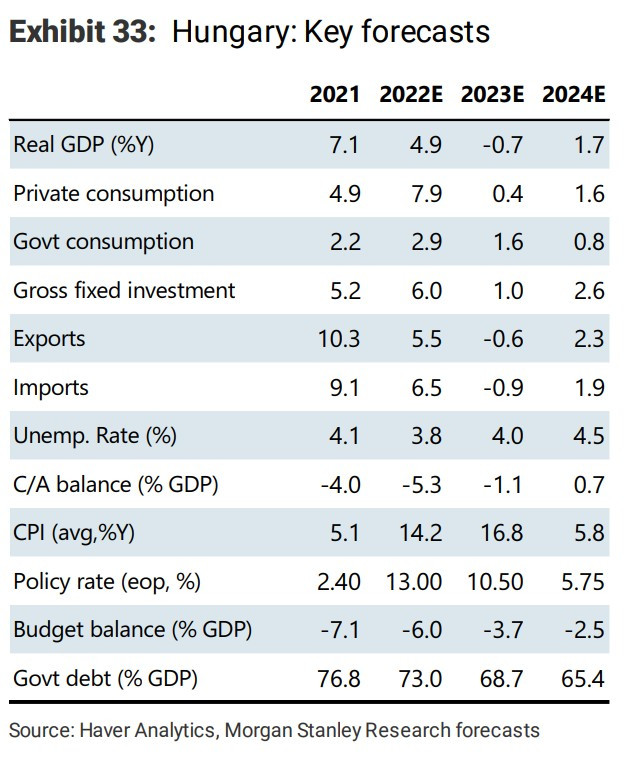
Morgan Stanley sees inflation remaining elevated and above 20% year on year in Hungary in the first quarter of 2023 before starting to decline more visibly in the second half of next year.
It projects headline inflation to enter the central bank’s tolerance band (3% +/- 1ppt) only in Q3 2024, “helped by slower global inflation trends but supported by a still healthy labour market.”
In the near term, MS sees pro-inflationary risks persisting.
Imported inflation remains the main driver of overall inflation and is still causing domestic prices to adjust higher through ripple effects.
MS economists believe that the recent FX appreciation, if sustained through the fourth quarter of this year, would help those second-round effects to subside early next year but the full impact is likely to be felt only in H2 2023, when MS sees significant disinflation.
FISCAL-MONETARY POLICY
In CE3, the only country where the actual level of monetary and fiscal policy becomes tight (i.e.,a cyclically adjusted primary surplus and a positive real rate) is Hungary, MS said.
In Hungary, MS expects both the real policy rate and the cyclically adjusted fiscal stance to tighten materially in the next couple of years:
The government’s efforts to rein in the ballooning fiscal deficit from early this year are already paying off while disciplined public investment spending and the extra revenues from the windfall tax will be able to offset the decline in regular fiscal revenues on the back of the incoming recession.
Two-step easing cycle
With near-term inflation risks still skewed to the upside and global financial conditions continuing to tighten, albeit at a slower pace, MS expects the National Bank of Hungary (MNB) to keep its base rate and liquidity-focused policy framework unchanged until the first quarter of 2023.
We see the central bank starting to ease policy by delivering a first 100bp cut in the 1-day depo at its March core meeting and expect it to continue to do so until it converges to the base rate at 13%.
Past that stage, Morgan Stanley sees the central bank moving at 50bp steps at each of its meetings in the second quarter of next year and only slowing down the easing pace in H2 2024. All in all, MS sees the base rate reaching 10.50% at end-2023and 5.75% at end-2024.
MS expects the base rate to decline less in 2023 than Bloomberg consensus expectations of 9.70% for 2023.

As regards risks to the interest rate projections, MS noted that in the bear case of tighter global financial conditions and higher imported inflation, they see the central bank tightening monetary conditions through the 1-day depo rate by hiking it closer to the upper bound of the interest rate corridor, currently at 25%. In the bull case of lower global inflation pressures and less stringent financial conditions, they expect a faster and deeper easing cycle from the MNB.
Budget deficit
Morgan Stanley sees the government sustaining a path towards fiscal consolidation following the rapid expansion of fiscal spending in the first half of this year. It projects the general government deficit to decline from 6.0% of GDP in 2022 to 3.7% in 2023 and 2.5% in 2024.
Yet, under our assumption of the government securing EU funding, the pre-financing period of the new MFF will mean larger cash-based government deficits in the next couple of years.
Current account at peak deficit
The higher energy import costs this year have been the main driver of the significant deterioration of Hungary’s current account deficit, which Morgan Stanley expects to come out at 5.3% of GDP. Yet, with gas prices stabilising already in the fourth quarter, they expect the C/A gap to start improving already and to gradually improve to 1.1% of GDP in 2023.
Relatively lower oil and gas prices in 2024 together with muted domestic demand growth dynamics will help the current account to reach a 0.7% of GDP surplus in 2024.
Cover photo: Getty Images





