Hungary cenbank to hold policy meeting with very few open issues


Number of unknowns: very few
It is almost certain that the base rate will remain at 13%, and the two ends of the interest rate corridor at 12.5% and 25%. But these are not really of much significance, as the benchmark rate since mid-October is the 18% one-day deposit rate, which is decided every morning by the central bank. There is currently no reason for the central bank to change the interest rate conditions.

In the current situation, only the top of the interest rate corridor would be relevant, as it limits the scope for further policy tightening. However, the 25% interest rate level seems sufficient for now, with ample room to raise rates further if necessary.
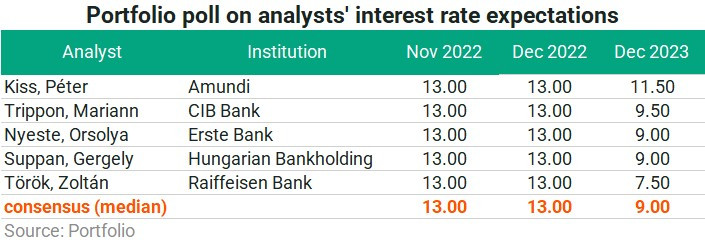
Analysts surveyed by Portfolio are unanimous in their view that there will be no change to the 13% base rate, and do not expect any further hikes in the longer term. In other words, the next step for the base rate could be a rate cut sometime in 2023, when inflation is expected to start its retreat.
The key question now may be what the central bank will communicate following the decision. The market mainly wants to find out how long the current system of daily decisions on the benchmark rate, which is 500 basis points above the base rate, will remain in place. From there, it is likely that the MNB will make the base rate the benchmark again via gradual cuts, but the question is when and at what level.
Orsolya Nyeste, an analyst at Erste Bank, does not project any changes to be made on Tuesday, saying the MNB is expected to reaffirm its strong "whatever it takes" stance. A month ago, the MNB gave a strong signal that it would stick with the current monetary framework until there was a sustained improvement in risk perceptions. And over the past month, there has been only a minimal improvement on this front, reflected in the normalisation of longer-term yields rather than the exchange rate, she stressed. She highlighted as a risk that the EU funds issue remains unresolved, to which the market appears to be very sensitive, while the inflation picture seems to be deteriorating again.
Péter Kiss, Investment Director at Amundi, believes that if an agreement on EU funds is reached (there's EUR 7.5 bn + EUR 5.8 bn on the line), a slow, gradual reduction in interest rates could start as early as this year, which could even bring the 1d depo rate down to the level of the base rate.
Regarding the macroeconomic outlook, the central bank may confirm that a turnaround in growth has started and that a substantial deceleration in GDP growth is expected in the coming quarters (technical recession is likely), which, together with external factors, could lead to a turnaround in inflation. The MNB may also communicate a cautious sangfroid on the external equilibrium, says Mariann Trippon, analyst at CIB Bank, the local arm of Italy's Intesa Sanpaolo. She believes that it will be many months before the turnaround outlined by the MNB is "demonstrable", while the macroeconomic outlook remains subject to a high degree of uncertainty and risk - so monetary easing is out of the question for the time being.
How long will we need to watch the daily rate decisions?
The MNB's communication over the past month or so was interesting to watch because in mid-October it still stressed that the one-day deposit quick tender was expected to be a short-term measure. In contrast, no change was applied to the tender ever since, with the rate remaining 18%, meaning that there is no sign of any convergence between the base rate and the benchmark rate.
Analysts are unanimous that the two interest rates will only converge in 2023, meaning that the central bank will not rush to lower rates. The general expectation now is that the base rate of 13% will not rise further, but that the benchmark rate will slowly fall back to the same level as risk perceptions gradually improve.
Opinions are still strongly divided on when the central bank may cut the 1d depo rate for the first time, with roughly as many expecting it to happen in the fourth quarter of this year as in the first quarter of 2023. This is likely to depend largely on the outcome of EU negotiations, inflation developments and international sentiment.
Forint exchange rate - Anything goes
Of course, the central bank's decisions and communication not only have an impact on the forint exchange rate, but it also depends on it. One only has to look back to mid-October, when the almost unstoppable fall of the Hungarian currency could have prompted the MNB to turn around.
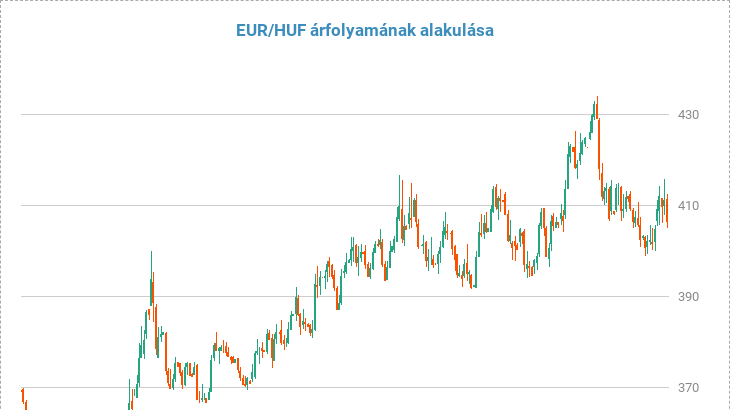
In recent weeks, one thing has been certain about the forint: the exchange rate has been subject to significant, larger-than-usual fluctuations. At the same time, it is now almost unpredictable where the exchange rate will go, with a fairly wide band of "anything is possible". And this is reflected in the analysts' views, with experts forecasting a range of 360-430 for EUR/HUF over the next year.
In other words, a significant, up to 10%, HUF appreciation is on the cards, but the forint could also return to the low seen in early October.
The country's risk perception remains extremely fragile, as reflected in the forint's recent volatility, commented Mariann Trippon. In addition to the tangible fundamental improvement, the EU agreement is another factor that markets are paying close attention to. Although she expects an agreement to be reached, there are no concrete details yet, only contradictory statements (see links above).
According to the CIB analyst, the past few weeks have clearly shown that premature moves in the current environment will backfire immediately, so the MNB needs to be extra cautious when setting monetary conditions.
Cover photo: Getty Images





