Sad news for Hungarian workers: wage boom is not exactly around the corner


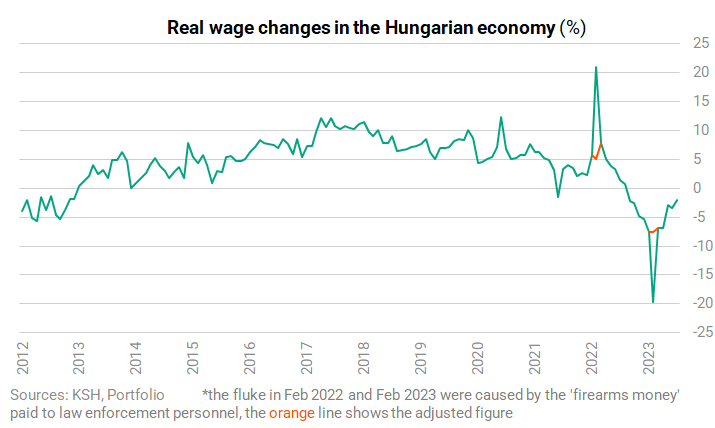
Real wages in Hungary have been falling for almost a year, after the country recorded the sharpest rise in consumer prices in the European Union for most of the period. However, inflation of over 25% seen at the beginning of the year has fallen to around 12% by now, lower than the rate of wage growth of between 15% and 16%.
In other words, we can say that real wages did not fall in August and that they rose again in September.
This ends the decline in real wages that started in September last year. And the coming months will see even higher real wage growth, as annual inflation is expected to fall month by month, while the wage index should remain stable above 15%.
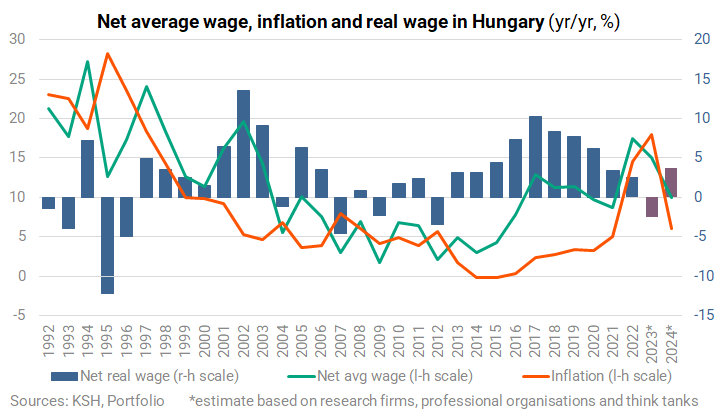
But this alone will not make workers happy. To understand why not, we need to start the story a little further back, with the link between gross wages and inflation and the illusion of year-on-year indicators. Wages in Hungary have been growing at a brisk pace in recent years, and the rate of earnings growth this year is not to be smirked at either (although there is a constant contradiction between the two sets of statistics from the Central Statistical Office). The average wage has also increased by a similar rate.

The problem is that inflation has obliterated wage increases. The rate of inflation was stubbornly high, so with inflation at 25% we started the year with a real wage dip of over 7%, which lasted until the beginning of the second quarter. July saw another "only" 2% decline as annual inflation eased, August saw wage purchasing power near stagnation, and the index returned into positive territory in September.
Many people infer from this context that the bad times are over. But why do workers feel none of this positive change? It is because it is just a statistical effect.
The fact that wages are now rising faster than prices compared to the same period last year does not mean that there is any improvement compared to previous months, as wage increases are not monthly but mostly annual.
With prices usually rising compared to the previous month - and falling only exceptionally - it is not surprising that high inflation eats into wage increases. The graph below shows exactly how gross earnings and real wages have evolved month-on-month on a fixed basis (compared to 2020):

Real wages are currently 10% above the level recorded in early 2020, but no higher than they were in 2021. At the same time, they are not lower than at the beginning of this year, although the annual wage index would suggest that the turnaround is here. It is fair to say that the deterioration in real wages has already stopped on a short basis, with most of the real value loss of our earnings having been realised earlier.
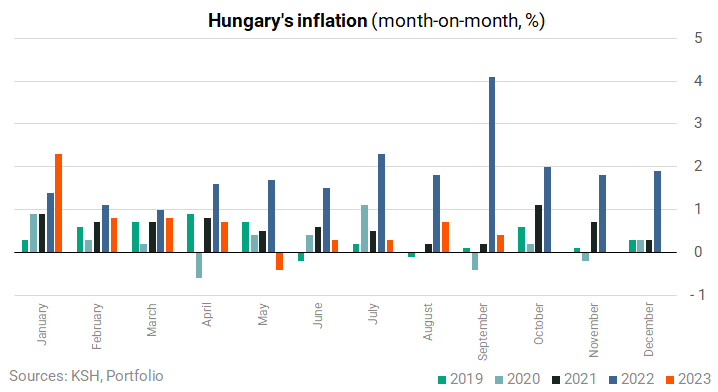
The reason behind this is that last year, and in January-February this year, there was a huge month-on-month price increase. But after that, m/m inflation was subdued, with a fall recorded in one month, May.
So, overall, we left most of the price increases of the past two years behind us in 2022. Prices had already soared by the end of last year and have continued to rise at a slower rate this year. As the monthly inflation figures show, the m/m increases are not as dramatic as before, which is the cause why the real wage index on a monthly basis has been flat for some time.
This is also important because people are not concerned with how much their wages have increased or how much prices have risen compared to the same month last year, but whether they have found it easier or harder to make ends meet compared to the last few months.
Most people don't even remember what certain products or services cost this time last year. So no one will care now that the annual real wage has moved into positive territory (as we highlighted above), as this will not really make them feel any better than they have in the last few months (as most people will have to wait until at least January for their wages to be raised).
And this is why retail sales have not been able to grow for months.
Even though year-on-year inflation has fallen steadily - largely due to the base effect - from a record high of 25% to close to 12%, people are not buying more (in volume) because prices continue to rise, albeit slowly, on a monthly basis, while their wages do not go up during the year.
To understand all aspets of this, it is worth looking at retail trade in the same way as we did with wages. The trend between annual and monthly retail sales is similar to that for wages.
The graph below shows that the year-on-year decline in retail sales has been getting smaller. After the 12-13% drop seen in the spring, the decline is now "only" 7%. However, this is exactly the same deceptive annual index as we have seen for real wages. Even though the yr/yr decline is moderating, retail is in fact no better (or less bad) shape than it was in the months of the double-digit contraction. In fact, the performance is even worse.

So how come we are no longer seeing double-digit declines? It is because as we move forward in time, the annual decline is relative to lower and lower bases (lower purchase volumes). So the decline in sales doesn't seem as large now as it did before.
This is why it is worthwhile to consult the month-on-month retail statistics. As shown in the chart below, retail sales have been falling steadily since March last year (the annual index was late to indicate this, only turning negative in December).
Even if we look beyond the market-distorting price freezes, petrol tourism and a series of government transfers, the graph below shows that there was already a problem from the middle of last year. By August this year, retail sales volumes had fallen to a level as low as where they were at the start of 2019.

But here too, what we have already seen in the case of wages applies: in fact, retail sales volumes are barely falling, and in the last three months we can even call the performance stagnant on a monthly basis.
If we start from real wage trends, this is perfectly understandable: wages do not really increase during the year, but inflation has also tamed over the summer months, so real earnings and retail sales move quite closely together. (Of course, this should not necessarily be the case, as there are many other factors that can affect propensity to spend.)
Turning things around, it is also worth saying that in fact the double-digit year-on-year decline seen this spring is not as much of a tragedy as the index would suggest.
It just so happened that the base was the last moment before the consumption bubble burst, the period when even those who didn't know whether they had to stop in Bucharest or Budapest wanted to pump gas in Hungary, while the families' personal income tax refunds and the 13th-month pension were fuelling retail trade. It is precisely because of such individual factors that we sometimes see large swings in the year-on-year indices.
As with the rise in price levels, the fall in consumption was already over the worst in the second half of last year and the beginning of this year. After record consumption during the election period last year, we saw a rapid decline - as shown in the graph above, the consumption bubble burst - while since February this year we have seen 'only' a slow decline.
Of course, this is not good news at all, as it shows that the population has been forced to keep a watchful eye on their spending ever since, but the short-term trend is much better than the yr/yr real wages or yr/yr retail sales data have shown over the past six months.
Overall, nothing so spectacular has happened to wages and inflation (and hence real earnings) in recent months, as the annual indices suggested, which could show real wage growth of up to 6-8% by the end of the year.
How's the outlook?
Although the year-on-year real wage index turned positive in September, this does not mean that retail trade will suddenly take off, as prices continue to rise and workers typically do not receive mid-year wage increases this year. Real wages have been virtually stagnant for months (compared to previous months), in fact there is a statistical effect behind the turn in the annual index.
But when will the real turning point come? Wages are typically raised in January or at the end of the financial year. The minimum wage (and the wage minimum for skilled workers) gets raised at the beginning of the year, and most wage agreements are concluded at this time of year. And companies with a fiscal year other than the calendar year usually raise wages in the spring. So however nice the year-on-year wage index looks this autumn, workers will not feel much change. Rather, it will be the conclusion of wage agreements that will be the turning point.
So we may still have a bleak couple of months ahead - perhaps helped by a one-off compensation for minimum wage earners - but next year could bring some respite. The minimum wage could rise by 15% and the guaranteed wage minimum by 10% in 2024, while the average wage could also rise by double digits. With inflation expected to be "only" around 5-6% next year, real wages could rise again after this year's decline.
Importantly, however, the macroeconomic outlook is currently extremely uncertain and it is not yet clear how strong the repricing will be in January. Weak retail sales point to lower repricing, while retrospective inflation-based pricing and significant wage pressures from continued meaningful labour shortages point to higher repricing. And employers and employees cannot breathe a sigh of relief until inflation returns to near the 3% target. And that won't happen any time soon.
Cover photo: Getty Images