Warning from Brussels: Hungary will overshoot deficit targets for years


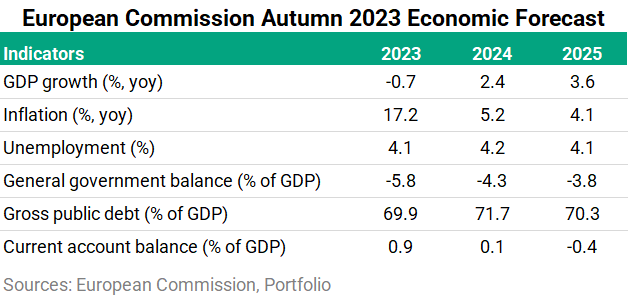
On Wednesday, the European Commission published its usual autumn economic forecast, according to which Hungarian GDP could shrink by 0.7% in 2023, from where growth could pick up to 2.4% next year and 3.6% in 2025. Inflation could average around 5% next year, before slowing to 4%.
"Consumption is set to be supported by recovering real income growth and the easing of precautionary saving. Construction investment is projected to remain constrained by fiscal consolidation and high interest rates, but large FDI projects in manufacturing are expected to boost machinery investment. As these capacities enter production, they are set to gradually bolster Hungary’s export performance," the EC said.
The Commission forecast shows that the Hungarian budget faces serious challenges. The 2023 target has already been raised by the government from 3.9% to 5.2% of GDP, but even this will not be met, with a deficit of 5.8% of GDP projected by the EC for this year. Next year, the slippage could be even greater, with a deficit of 4.3% against a target of 2.9%, but even in 2025 the deficit is expected to be 3.8%.
So for the time being, the commission believes that the Hungarian government is still years away from reaching the coveted 3% deficit target.
As a result, the debt-to-GDP ratio is projected to rise to 71.7% in 2024 from 69.9% in December this year.
Lower global energy prices and loosening financial conditions will help the Hungarian economy to recover, the Commission says, while on inflation, it stresses that wage increases remain a risk.
The budget deficit is projected to remain elevated beyond 2023, reflecting the impact of lasting revenue-decreasing measures adopted in recent years,
the Commission said.
It also noted that the country's external balance has been improving sharply in 2023 owing to lower energy import prices and lower imports due to the economic recession. The current account balance is set to turn from a deficit of -8.2% in 2022 to a surplus of 0.9% in 2023. However, with the projected recovery of domestic demand the current account is forecast to revert to a small deficit by 2025.
While noting the retreating inflation (from extremely high levels), the Commission warned that high wage growth is expected to keep service inflation persistently high. "Although the aggregate profitability of the corporate sector appears high, smaller companies are assessed to be more financially stretched, thus they are more likely to pass wage increases on to consumers."
The excise duty hike of motor fuels in January 2024 is estimated to add 0.5 pps. to inflation in 2024.
The harmonised inflation rate is forecast to decrease from 17.2% in 2023 to 5.2% in 2024 and 4.1% in 2025.
Downside risks to the growth outlook stem from a sudden increase in the country risk premium which might also constrain fiscal policy, and from the high exposure of the economy to a potential spike in energy prices. Upside risks to growth and inflation are related to potential stimulus measures such as larger-than-expected minimum wage hikes.
The higher-than-expected budget deficit is driven mostly by underperformance of revenue, in particular VAT, reflecting weaker-than-expected economic performance in the first half of the year, and higher spending on interest and pensions due to high interest rates and inflation, the EC added.
Revenue growth is expected to be hampered by the deficit-increasing impact of the permanent tax cuts since 2019 and the planned phasing out of the sectoral and windfall profit taxes in 2025, with an estimated impact of 0.7% of GDP. Growth of current expenditure is set to be restrained in 2024.
High interest expenditure will weigh on the budget in the coming years due to high nominal interest rates and high coupon payments on inflation-indexed retail bonds.
Nationally financed public investment is expected to fall substantially over the forecast horizon, while the EU-funded investment projects are set to accelerate. Subsidies to utility companies to cover losses from regulated energy prices are projected to fall, driven by moderating gas import prices.
The net budgetary cost of the measures to mitigate the impact of high energy prices, including the windfall profit taxes collected from the energy sector, is projected at 0.8% of GDP in 2024, compared to 1.3% in 2023.
Upside risks to the deficit stem from the persistence of high interest rates and inflation, exposure to energy commodity prices, and the subdued level of current expenditure, especially on wages, the EC concluded.
Cover photo: Getty Images





