Hungary central banker reveals next rate move, setting path for the forint too


Rate meeting outcome is already set
In October, the Monetary Council of the MNB cut the base rate by 75 basis points to 12.25%, while analysts had expected a smaller cut of 50 basis points. Since then, the October inflation figure has been lower than expected, slipping below the 10% mark (9.9%), leading many to speculate that the MNB might even accelerate the pace of rate cuts. These expectations were quashed by Deputy Governor Barnabás Virág at a conference on Thursday, who effectively announced that maintaining the 75 basis point rate was justified.

Virág also made important statements on the future interest rate trajectory, as he expects the benchmark rate to be cut below 11% by the end of December, and then to be below 10% for the first time next February. This could mean an unchanged easing of 75 bps at each of the the next four meetings.
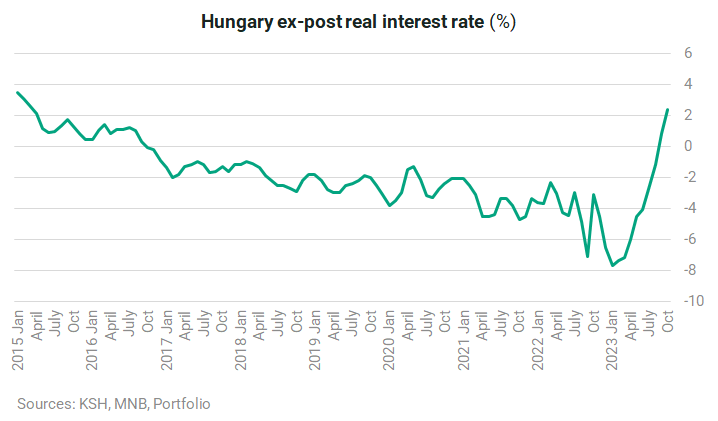
The key metric guiding the central bank at the moment is the ex-post real interest rate, which turned positive for the first time in a long time in September. Speaking on Thursday, Virág said that a positive reading could be expected for months or even years. Currently, with inflation at 9.9% in October and the base rate at 12.25%, the ex-post real interest rate is 2.35%, meaning there is plenty of room to lower rates further.
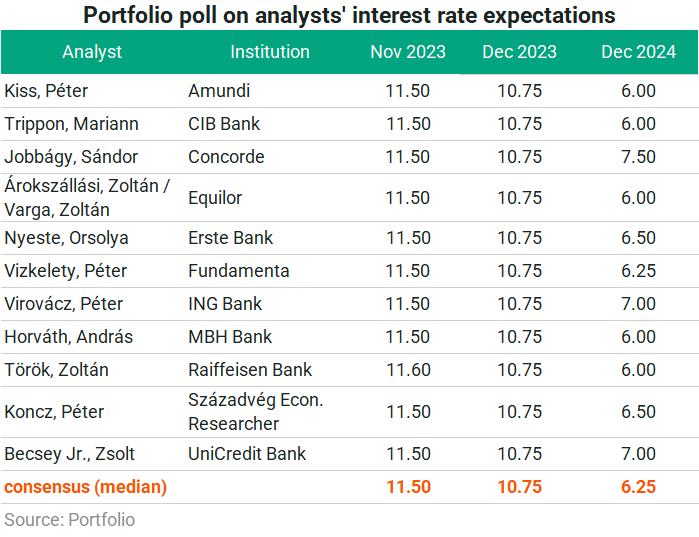
Unsurprisingly, analysts polled by portfolio are all expecting a 75 basis point rate cut after virág's remarks, and the same reduction is expected in December.
Based on the central bank's strongest forward guidance to date, the rate-cut cycle could continue at the pace started in October until February, which is broadly in line with our current expectations, stressed Péter Kiss, Investment Director at Amundi.
Events have turned out favourably for the MNB over the past month, as reflected in the strengthening of the forint,
commented Zsolt Becsey, analyst at UniCredit Bank in Budapest, according to whom, this is mainly due to the recent U.S. data and the resulting increase in risk.
Overall, both real economic and financial market data favour a continuation of the 75 basis point rate of decline, compared with our previous baseline forecast of 50 basis points, Becsey added.
In October, the central bank cut the base rate more than what the market projected, but despite this, the forint did not experience significant fluctuations and strengthened. In November, the macroeconomic environment was also favourable, with inflation falling more than analysts' consensus and the MNB's forecast, and the current account balance is also better than expected. These factors could even predetermine a larger interest rate cut, but the geopolitical situation remains vulnerable and avoiding HUF depreciation is key for long-term price stability, Péter Koncz, junior analyst at think tank Századvég, outlined the background to the expected decision.
In the coming months, the Monetary Council will remain in a data-driven mode, deciding on its actions step-by-step based on incoming data and with a strong focus on financial market stability, said Mariann Trippon, despite strong guidance from the Deputy Governor. According to the analyst at CIB Bank, there is room for a cut of up to 100 basis points based on the data received in recent weeks, but the MNB is expected to focus on caution and predictability.
"In my view, the central bank is now carefully weighing potential gains and losses, and the balance is unfavourable for a larger reduction than last month," stressed Péter Virovácz. The analyst at ING Bank said the reason for this is simple: politics has put too much pressure on the central bank, and the cabinet has essentially shot itself in the foot with this.
Even though there are plenty of real professional reasons to step up the pace of rate cuts, a significant proportion of foreign investors - who follow domestic economic and political events only superficially and are only informed by headlines - would oversimplify the issue and see it as a bowing to political pressure. And the very assumption that this train of thought could be turned around in the minds of investors is now acting as the greatest possible disincentive. Quite rightly, I might add, Virovácz pointed out.
How to proceed in 2024?
The pace of interest rate cuts could continue in the first two months of 2024, as forecast by Barnabas Virág, unless there is a major shock, said Zoltán Árokszállási. On the inflation front, the analyst at Equilor said it will be important to see how pronounced the repricing at the beginning of the year will be. If we didn't see too sharp hikes in this area in the first months of the year, that would be very good news and could make the subsequent rate reduction path more certain.
Overall, analysts are not expecting any big surprises from the central bank next year, with an average forecast of 6.25% for the base rate by the end of 2024, and forecasts ranging between 6.0% and 7.5%.
The upside risks to next year's inflation outlook include the pace of recovery in domestic demand, real wage growth of 4-5%, the forint exchange rate, the extent of repricing at the beginning of the year, and possible external shocks, said Mariann Trippon, commenting on the outlook for 2024.
According to Péter Virovácz, the 75bp rate cut pace is unlikely to change before next spring. In his view, the disinflation process will slow down substantially after the first months of the year, when base effects will no longer be so supportive. In parallel, the pace of monetary easing may be slowed down to maintain sufficiently high real interest rates, and eventually the base rate may be anchored at 7% for a longer period.
In this environment, it seems that there is still room for relatively large steps, so that the real interest rate level, which is considered to be the key in the MNB's communication, remains relatively high, said Orsolya Nyeste, analyst at Erste Bank.
What will happen to the forint then?
The question is what impact the central bank's policy outlined above may have on the forint. On the one hand, Hungary's interest rate advantage may gradually diminish, as no similar easing measures are expected in the region. On the other hand, the MNB has outlined a predictable path with its recent statement, which could be important for investors.

With the move in November and December, real interest rates could rise by a further 1.5% from current levels by the end of the year, to the highest level in the region, making Hungarian assets increasingly attractive to foreign investors,
stressed Péter Kiss at Amundi.
Péter Koncz agrees, arguing that inflation is expected to fall faster than the base rate in the coming months, so the emerging real interest rate will become more significant in the near future, which could
support the stability of the forint exchange rate.
"Despite expectations for further rate cuts, we do not expect the forint to weaken significantly," said \Péter Virovácz. Firstly, the external balance and the marked improvement in the current account balance may offset the impact of the interest rate reductions, underpinning the forint. Secondly, the easing cycle and the normalisation of domestic interest rates have already been priced in by the futures markets. And thirdly, the real interest rate has already turned positive, and the steep decline in inflation may lead to a substantial widening in the coming months, thus the expected yield may also decline, the ING Bank expert added.
Cover photo: Portfolio





