Hungary cenbank accelerates rate cut pace to 100 basis points


In recent months, there has been increasing pressure on the central bank - mainly from the government - to accelerate the pace of monetary easing. At the January Monetary Council meeting, two members already voted for a 100 basis point cut, indicating that the issue of acceleration was on the table. In fact, the MNB had already begun to lay the groundwork for an acceleration in the previous days through its communications and was clearly intent on moving towards a more pronounced easing. However, it abandoned this at the last minute and has not decided to cut interest rates more, putting off the greater reduction to February.

Not black and white
Behind the current decision on monetary policy lie all the big questions for the Hungarian economy. The easiest way to understand them is
in terms of the inflation-growth-financial stability triangle.
The main argument for switching to a 100bp rate cut was the faster-than-expected fall in inflation. January's headline figure came in at 3.8%, bringing the index within the central bank's target range of 2-4%. This suggests that inflation has been devouring itself: the recession and the contraction in real wages have curbed demand-side price increases and prevented expectations from getting stuck high. In addition, the correction in energy prices, the passing of the food price shock and the strengthening of the forint have helped. (We’ll discuss this in more detail later on.)

Perhaps the most unpleasant surprise of the past month has been the worsening of the growth outlook. In the fourth quarter, the Hungarian economy stagnated, with growth recorded only once in the last five quarters. The weak performance in Q4 suggests that the recovery may be slower than expected, as suggested by the information coming from the global economy.

Based on domestic industrial production and labour market data, the government's 4% growth target for this year is increasingly subject to downside risks. While high interest rates are not the primary reason for this, the easiest of the tools for a high-pressure economy seems to be to boost lending, which requires lower interest rates. In other words, faster interest rate cuts could be used to support growth, if the MNB sees room for manoeuvre.
From a financial stability perspective, the timing of this interest rate decision was more rewarding than the one in January. Although the euro was still flirting with 390 against the forint, there has been less volatility overall in recent weeks, investors' risk perceptions have not been exacerbated by economic policy ideas or even the tense relationship with the EU, and the international environment has also been more favourable. If it was the fear of the market’s reaction that deterred the central bank from cutting more in January, it could have been bolder in February.

In view of the above arguments, one could call it a no-brainer that the MNB lowered the base rate by 100bps today, but in fact there were at least as many arguments for a more cautious approach.
75bp pace could have been maintained
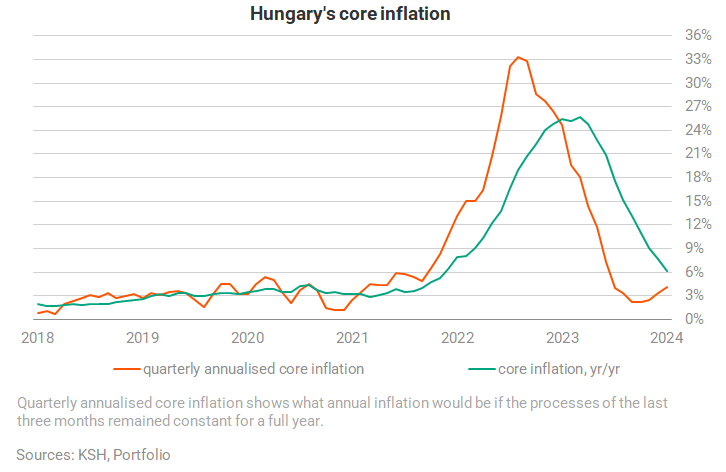
While the rapid disinflation continued with inflation at 3.8% in January, there are several considerations that should help to nuance the picture. For one, the core inflation indicator, which captures more persistent price movements, is still above 6%, and in recent months (on a short base) the indicator seems to have been on an upward trend. On this basis, it is not excluded that we are seeing the last months of disinflation, which is being replaced by a stagnation well above the 3% target or slight rise.
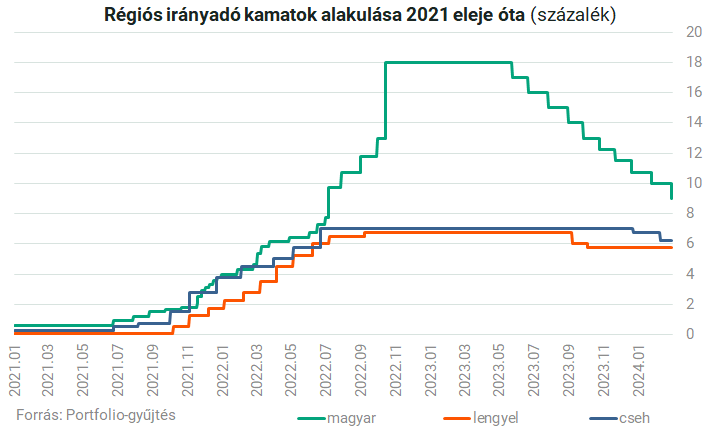
On the other hand, the international experience of the oil crisis period shows that central bank tightening that was stopped too quickly led to a resurgence of inflation. The risks from the geopolitical situation are also significant, with rising transport prices threatening to bring about new cost shocks, and it is no wonder that central banks in the major economies remain unconvinced that they have had their foot on the neck of inflation long enough.
In these circumstances, central banks think not twice but thrice whether they can contribute to the dynamism of an economy that is really struggling without jeopardising their primary objective.
As mentioned, the current investor sentiment on financial stability is more positive than a month ago. But the central bank does not think of this merely as a short-term consideration to pick the right moment.
In his Portfolio Checklist podcast, Zsolt Kuti, Chief Economist of the MNB, cited several examples from the past year and a half when a sudden deterioration in the international environment caused a risk premium shock that justified the central bank's more cautious stance.
Moreover, the news of the past week suggests that the European investment environment may become more risk-averse. Europe's banks have some €1,400 billion of outstanding loans in the ailing commercial real estate sector, which is a real concern right now because of the steep fall in office prices, the proliferation of insolvencies and the growing concern of investors and rating agencies about these exposures.
Meanwhile, the Hungarian economy is still perceived as worse than its regional peers. The budget deficit is high, growth challenges and the upcoming election period make a rapid reduction doubtful. This is coupled with high government debt by regional standards, so there is a good chance that investors will continue to expect some interest rate spreads in Hungarian assets.

In the light of today’s decision, it seems that, on balance, the MPC felt that arguments in favour of a bolder move were stronger. More on this will be revealed in the Council’s official statement to be released at 3 pm. and at the press conference starting at the same time.
In March, the policy meeting could be exciting again. On the one hand, we will know more about the intensity of repricing at the beginning of the year once we know the February inflation data, and on the other hand, the forecasts in the quarterly inflation report will provide a fresh guidance on interest rate policy.
Cover photo: Gábor Juhász





