Some people will be greatly surprised by the Hungarian central bank's policy decision


Over the past few weeks, investors have been speculating on how the central bank's series of rate cuts will continue after the MNB switched from its usual 75 basis point rate to a 100 basis point cut in February.
This was a little confusing for investors, but last week, in investor background discussions, a clearer picture emerged. In these, the MNB hinted at another 75-100 basis point rate cut in March (presumably depending on market turbulence), suggesting a slower pace in subsequent policy meetings.
The messages hit home on the market. At least the considerable rise in the consensus estimate for the end of the year suggest they did.
However, looking at analysts responses in Portfolio's monthly survey, we can see that the uncertainty has not completely disappeared. Two-thirds of respondents believe that the central bank will not risk another 100 basis point cut, mainly in view of the uncertainties in the financial markets and the volatile forint exchange rate, and instead it will return to the 75bp pace.
This would take the bae rate to 8.25%. In fact, some analysts are even more cautious, suggesting that it is now time to move to 50bp cuts that has been expected for the second quarter. However, there are also forecasts that the central bank will now go ahead with the 100 basis point reduction and then use communication (stressing the upcoming deceleration in April) to calm down disappointed investors.
There is almost unanimous agreement among analysts that the central bank will switch to a 50bp easing tempo from the second quarter.
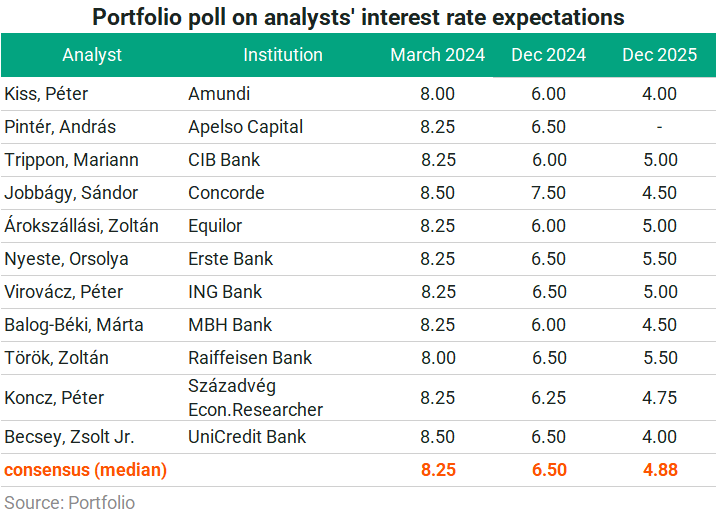
The explanation for the divergence in the short-term forecasts is, very briefly, that while inflation developments alone would allow for a strong easing, the fragile financial market situation requires an interest rate policy that ensures the stability of the forint (and some other financial markets). Failure to do so would have repercussions on inflation and the country's financial stability.
Why 75?
After the 100 basis points in February, we expect the Monetary Council to be a bit more cautious this time, and cut the rate by only 75 basis points again, said Orsolya Nyeste, analyst at Erste Bank.
While the fundamental picture would still allow for a 100bp reduction, as inflation remained in the target range in February to a small positive surprise, core inflation slowed sharply and the annual rate is expected to remain around 4% in March and April. However, the country's risk perception has deteriorated a lot in recent weeks, mostly due to internal factors.
Annual inflation is likely to rise gradually again in the coming months, and political frictions over EU funds, the weakening forint, geopolitical tensions and volatility in international investor sentiment also warrant prudent monetary policy, said Márta Balog-Béki, an analyst at MBH Bank.
She expects the return to the inflation target to be slower and to take place only in 2025, so the rate cut cycle may slow down in the second quarter of this year.
In fact, macroeconomic indicators could allow room for a final 100 basis point cut, but for reasons of caution we expect a 75 basis point easing, said Zoltán Árokszállási, economist at Equilor.
Even after the last interest rate cut, the forint weakened more significantly, and the MNB would not risk it this time - even if the controversial draft central bank law and the possibility of a lawsuit over EU funds played a significant role in the weakening of the forint.
Mariann Trippon, chief analyst at CIB, also highlighted the risks. Tensions with the EU have not completely disappeared, and the fiscal situation and the increasingly vocal disagreements between different areas of economic policy (although they have calmed down in recent days) are worsening the country's risk perception, she added.
This has been reflected to a large extent in the forint exchange rate in recent weeks. While in February the exchange rate of the national currency stabilised (with the EUR/USD exchange rate typically fluctuating between 385 and 389) and did not underperform its regional peers, after the end of February EUR/HUF moved critically close to the 400 level and the forint clearly underperformed its regional peers. Since then, we have seen a correction in the exchange rate, but it is still stuck above 390.

Presumably, two scenarios will be on the agenda again, 75bp and 100bp, and in the light of the market reaction following the last decision and the subsequent communication of the central bank, we believe that the "temporary acceleration" of the base rate cut may already be slowing down, said András Pintér, economist at Apelso Capital.
However, it is not so much the March decision as the next three or four policy meetings that will be critical, and this will be emphasised in the verbal communication following the current decision, both in terms of the base rate range the central bank aims to reach by early summer and in terms of the fact that the month-to-month pace is highly data-driven. And when the central bank emphasises this data dependence, every investor will add one more thing: that of course it is also highly dependent on the exchange rate.
Or will it be only 50?
The slowdown to 50 basis points may be justified by the lessons of the market turbulence after the February vote (which was far from being the result of the decision alone, but rather of the general economic policy noise), explained Zsolt Becsey, analyst at UniCredit.
In his view, the MNB will focus on predictably reaching the 6-7% base rate target expected by mid-year. In the post-decision communication, it would not be a surprise to get guidance that maintaining the 50 bps rate could be the baseline scenario until mid-year. In this way, the MNB can also provide some buffer in case frictions between monetary and fiscal policy continue to dominate news flows, or in case any external events worsen the country's risk perception.
The MNB will also publish its latest macroeconomic forecast next week, in which it is likely to revise downwards its inflation and GDP estimates. These figures are expected to be close to the latest forecasts of market analysts and will therefore not have a market-moving effect.
Sándor Jobbágy, an economist at Concorde, also believes that a 50 basis point cut would be the most market-neutral move in view of the the forint exchange rate, money market pricings and sovereign spreads, and also taking into account domestic fiscal and inflation risks. While inflation has been on a positive trajectory in recent months, there is no longer any scope for a further substantial decline and the central bank's target is still unlikely to be achieved on a sustained basis in 2024.
Can the MNB stay bold then?
If the central bank stepped on the gas in February, it will try to stick to 100 basis points for at least one more time, after all, the 50 pace will come in April anyway, some experts say.
Risk sentiment has remained fundamentally unchanged since the previous decision, and recent central bank decisions and commentary on developed markets have tended to improve it, said Péter Kiss, economist at Amundi. The Fed's comments since the previous meeting have set the stage for another 100bp cut, which could be followed by a lower 50bp reduction in the coming months.
Zoltán Török thinks along similar lines. The senior analyst at Raiffeisen Bank sees a significant chance that the rate cut will be less than 100 basis points, but if the forint does not weaken further by then and the MNB gives strong guidance on the second quarter rate path, it may still hold out for a larger cut. Indeed, this guidance would mark a new phase in the rate cut cycle, with much smaller and less frequent rate cuts.
Cover photo: Gábor Juhász





