Hungary central bank keeps on cutting rates


In March, the MNB effectively said that it would cut interest rates by 50 basis points from April, i.e. it would start to slow the pace of monetary easing from the 75-100 basis points it has been cutting in recent months. The slowdown is understandable from several aspects:
- The period of rapidly declining inflation has ended, and from May onwards the indicator is likely to remain above the central bank's target range of 2-4% until the end of the year.
- The forint failed to stabilise at a stronger level, with the euro stuck above 390. This worsens the inflation picture.
- Interest rate cuts have brought yield levels elsewhere in the region within reach, and Hungary's risk premium relative to developed markets (especially the US) has continued to narrow.
The slowdown is so understandable that the question before today's decision was rather whether the central bank would not restrain itself even more. After all, the poor inflation data in the US has caused a stir around the world over the past two weeks. Rate cuts by the Federal Reserve have been priced out, yields have risen, and a sharply descending domestic interest rate path does not offer much of a premium to the 5.25-5.50% overseas policy range. One of the experts has even mulled over the possibility that the central bank may be forced to stop easing much earlier than it had intended, if it keeps its inflation and financial market stability objectives in mind.
However, the central bank stuck to its earlier plans and delivered the "promised" 50 basis point easing.

One reason why the central bank has not become more cautious may be that it has successfully used its communication tools over the past month to temper the market's exaggerated rate cut expectations. MNB Deputy Governor Barnabás Virág, MPC member Gyula Pleschinger, and MNB chief economist Zsolt Kuti all said that market pricings for the end of the year are too fragmented and overall too optimistic. The result has been a marked adjustment in interest rate cut expectations.
6x9 and 9x12 forward rate agreements (FRAs) were pricing a base rate of around 5.0% towards the end of winter, but by now they are up considerably at around 6.5-7.0%, while the 1X4 and 3X6 FRAs have mostly moved sideways around 7.5-8.0%. Thus, the yield reduction priced into products of different maturities has narrowed markedly, and in recent weeks the market has ended up pricing out significant price cuts previously priced in.
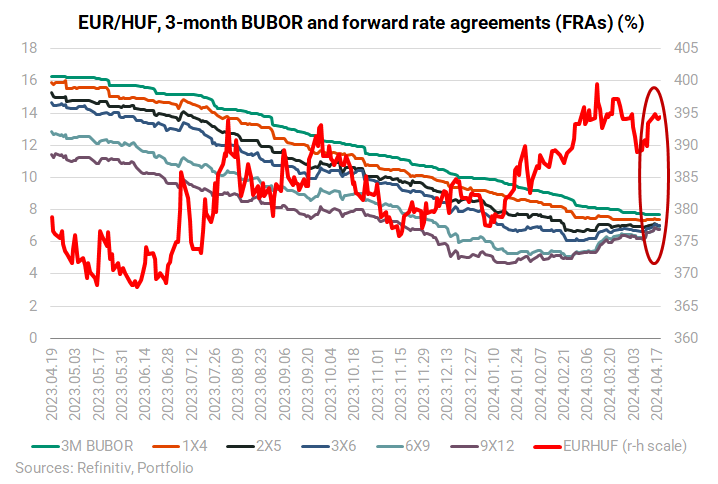
FRAs, the expectations of market analysts and central bank communication paint a similar picture for the future path of interest rates. The MNB may maintain the 50bp pace easing momentum until June, taking the benchmark rate into the 6.5-7.0 range by mid-year.
Of course, a lot can change between now and then, but unless something unexpected happens with domestic inflation or the international environment, the central bank will then scale back the pace of easing considerably, and it may even stop altogether.
The central bank may allude more and more to this in its upcoming remarks, possibly as early as today, at 3pm, when, as usual, Deputy Governor Barnabás Virág will discuss the rationale behind today's rate decision. A text version of the central bank's explanatory statement will also be published at that time.
Cover photo: Getty Images