Profit factory in Hungarian banking in full swing, here is a HUF 1 trillion surprise


The National Bank of Hungary (MNB) has recently published earnings data of banks for the first half of 2024, which show a consolidated profit of HUF 1,011 billion and a non-consolidated profit (e.g. excluding OTP's foreign subsidiaries) of HUF 972 billion.
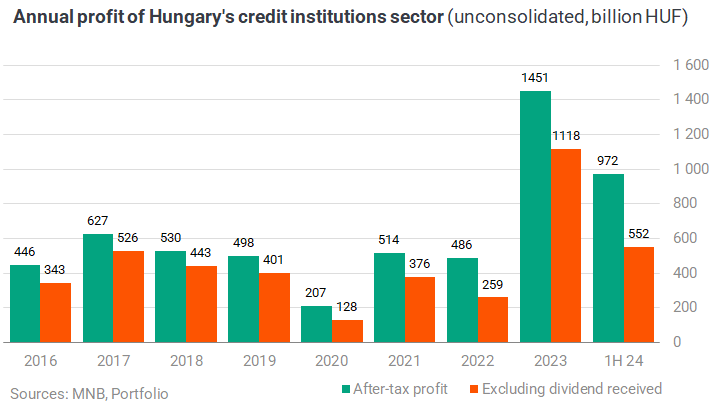
Without dividend income from mainly non-domestic banking activities, the latter would have amounted to HUF 552 billion. The first-half result was broadly evenly split between the two quarters.
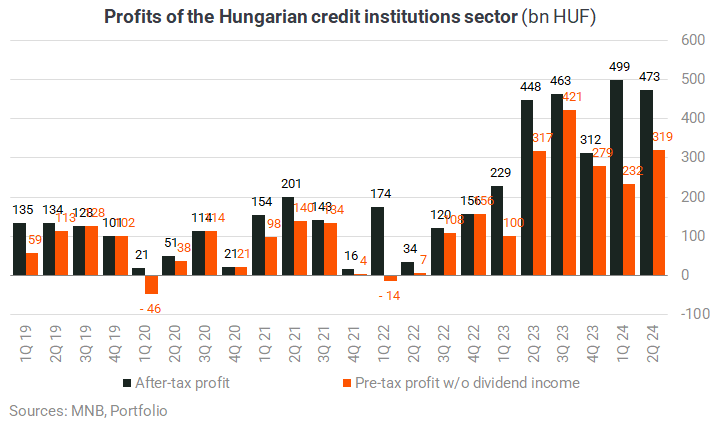
The raw earnings figure is 24.8% and the earnings figure excluding dividend income is 14.1% return on equity (ROE).
The former is a high level reminiscent of the period before the 2008 financial crisis, while the latter is not considered to be an outlier in the banking sector in the current interest rate environment. However, when corrected for other one-off items (see below), the return was somewhere between the two percentages mentioned.
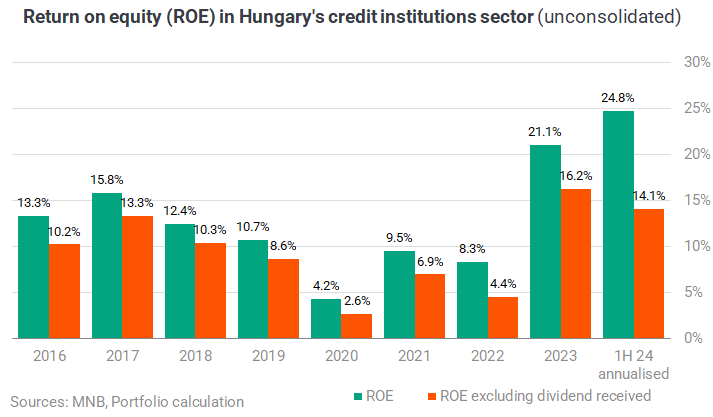
In the chart below, we have summarised the consolidated performance of each bank. Where we have not indicated the number, we have for the moment only an estimated figure based on the parent bank's earnings report. According to the MNB, four credit institutions were loss-making, but none of them were large banks.
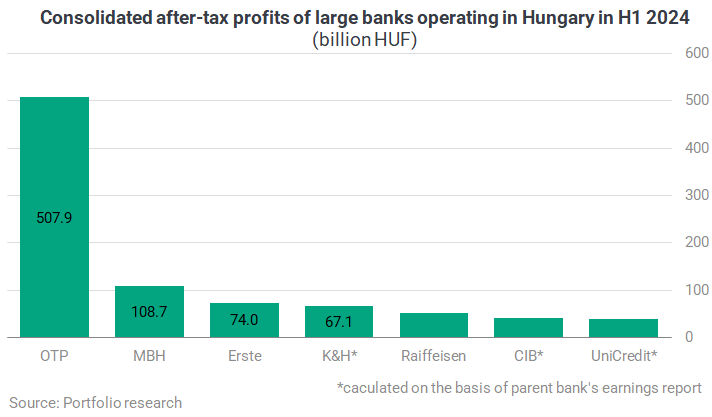
H1 profits in the banking sector were 44% higher than a year ago, even though the steep fall in the interest rate environment, which would lead us to expect diminishing profits, has already partly taken place.
If we look at what led to the growth in profits, we have to mention first of all trading income (e.g. the result of swaps and derivatives against various exchange rate losses), secondly the increase in dividend income,
and only thirdly the increase in income from core banking activities.
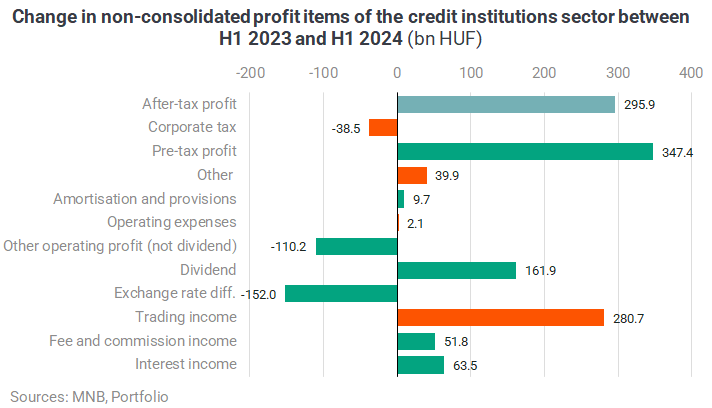
Net interest income was up 6% even in January-June of this year, reflecting the fact that while interest income fell due to the lower interest rate environment, interest expenses declined even more. However, the 11.6% rise in fee and commission income is quite flattering for banks.

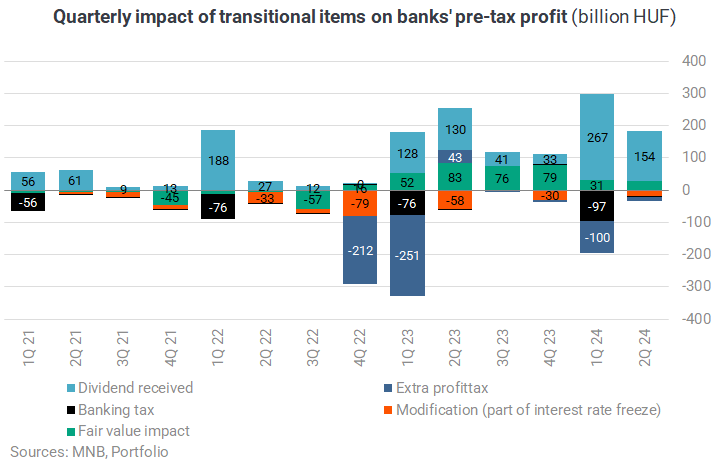
Meanwhile, operating costs shrank by 0.2% in the banking sector in the first half, as the windfall profit tax dropped to HUF 111 billion from HUF 208 billion in H1 2023. It is by no means certain that banks will be able to (largely) halve their extra profit tax burden this year as a whole, as the government has tightened the conditions for doing so. Banks will now have to increase not only their long-term but also their total holdings of government bonds, which some of them have most likely already given up to achieve this year.

One-off items other than dividend income and extra profit tax also affected banks' H1 results this year, for example, the adjustment loss recognised due to the further extension of the retail interest rate freeze by HUF -18 billion, while the fair value effect was HUF +60 billion.
However, the significance of these one-off effects was smaller in the second quarter than in the first, but they can still be corrected for. The total impact of the one-off items in our chart below was HUF +251 billion in the first half of the year,
so banks' profits would have been around three quarters of the raw HUF 972 billion figure without these one-offs.
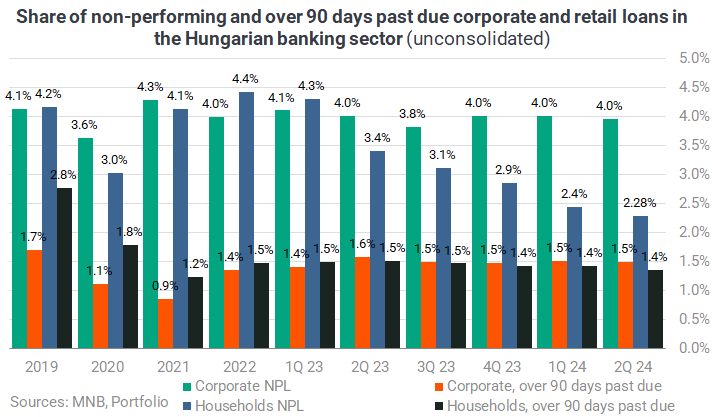
It is worth noting that impairment/risk provisioning and the quality of the loan portfolio remain a non-issue in the banking sector, with customer solvency remaining excellent and NPL ratios even declining slightly in the second quarter.
Finally, let's look at the banks' balance sheets on both the asset and liability sides:
the last few quarters have seen a slowdown in the dynamic rise in loan stocks, but the pace of growth in retail loans has returned to a fairly reasonable level,
as we wrote about in more detail recently.


Cover image (for illustration purposes only): Getty Images





