Hungarian gov't might need to make a bold move in interest rate cap system


As of 31 March 2024, the interest rate freeze on SME loans was abolished without causing a debt service shock for the thousands of SMEs affected. The interest rate freeze on mortgages, which has been in place since the beginning of 2022, is even tougher for the government, as
- it affects many more taxpayers (currently around 291,000), as it covers essentially all mortgages with an interest period of no more than five years.
- the reference rate for the loans concerned is capped at between 2.02 and 3.66% (on which the fixed mark-up is calculated), compared to 7.77 to 8.68% for SMEs, so its abolition would represent a bigger debt service shock.

We asked the central bank (MNB) what the stock is like now, and it turns out that
291,000 mortgages are affected by the interest rate freeze, with a principal outstanding of HUF 1,223 billion, representing 35% of all residential mortgage contracts and 19% of the total principal debt.

The measure has been extended several times by the government and is currently in force until 31 December 2024, i.e. by year-end it will have been in place for three years. Market and government sources alike expect another extension, but the big difference with the last few such decisions is that
the ascent of the yield curve has stopped and we are no longer approaching the low interest rate levels of when the rate freeze was introduced.
Indeed, the BUBOR (Budapest Interbank Offered Rate) has reversed from a low of 6.0%-6.3% in early October to 6.4%-6.5% in recent weeks, and benchmark rates for 3-year and 5-year loans have started to rise again. With the central bank's base rate reduction paused at 6.5%, BUBOR could settle around this level indefinitely.
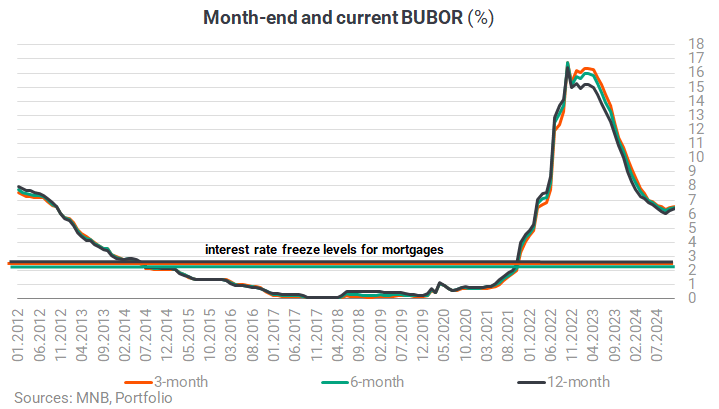
If the interest rate freeze were to be scrapped now, the average interest rate on mortgages with an interest rate freeze would rise from around 6% to close to 10%.
Loans with variable interest rates within a year, linked to the BUBOR, account for two thirds of the loans with interest rate caps. For these, the interest rate increase would be even higher, averaging 4.5 percentage points, due to the difference between the current and the fixed BUBOR.
The repayment of a typical housing loan of HUF 4 million outstanding and with a remaining term of 5 years would increase by 11% with such an interest rate increase. The longer the remaining maturity, the higher the percentage increase in repayments would be, but fortunately, the average maturity of the loans covered by the interest rate freeze is relatively short, with the average being somewhere around five years.
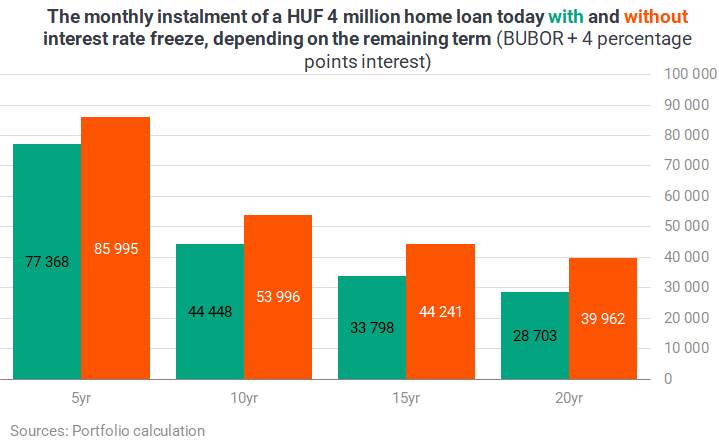
The low residual maturity also explains why, according to the MNB's May Financial Stability Report,
the possible phasing out of the interest rate cap may only lead to a substantial increase in the repayment burden for a small group of clients.
According to the central bank, the burden may increase more sharply for some customers: nearly 26,000 customers subject to the interest rate cap (9% of fixed-rate customers, 17% of fixed-rate mortgages, less than 4% of total mortgages) are considered vulnerable in terms of their ability to repay (i.e. their monthly repayment instalments would increase by at least HUF 5,000 if the measure is discontinued. Moreover, their DSTI (debt-service-to-income ratio) will reach 50% or higher, or they have reached retirement age, resulting in a negative income shock, since the measure was introduced).
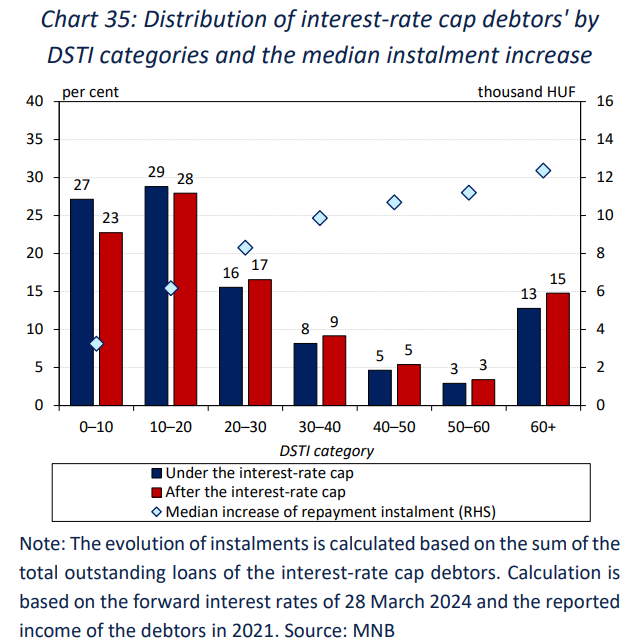
The vulnerability of households to interest rate rises is also gradually diminishing as real wages rise, so it may be timely to phase out the the interest rate cap. Government officials have previously linked this to two important conditions: a fall in interest rates and a pick-up in consumption:
- In May 2023, Gergely Gulyás, the PM's chief of staff, told journalists that the interest rate freeze will be phased out when the central bank base rate falls below 10%,
- In September 2023, Economy Minister Márton Nagy said in an interview with Portfolio that "we can phase out the interest rate freeze on retail loans at least in two steps. The justification for the first step will be examined once we take action on SMEs, so likely in January. But if household consumption is feeble, even the first step could be delayed."
- In May 2024, Márton Nagy said at a conference of the Hungarian Banking Association that the retail interest rate freeze will be lifted when consumption recovers.
Single-digit interest rates are back, but consumption just wouldn't take off. So it is highly doubtful that the government now thinks the interest rate cap can be ditched on the basis of consumption.

The measure has already cost the banking sector more than HUF 400 billion, and as BUBOR starts to rise, the bill will continue to rise on a pro-rata basis. For banks, an immediate complete phase-out would certainly be the best option, as the increase in their risk costs due to defaults caused by a rise in repayments would be much smaller than the cost of maintaining the measure.
We understand that, as a compromise,
the banks would also agree to a phased abolition, for example by combining the abolishment of the interest rate cap with a burden-sharing arrangement similar to the former government-backed exchange rate cap system for fx loans.
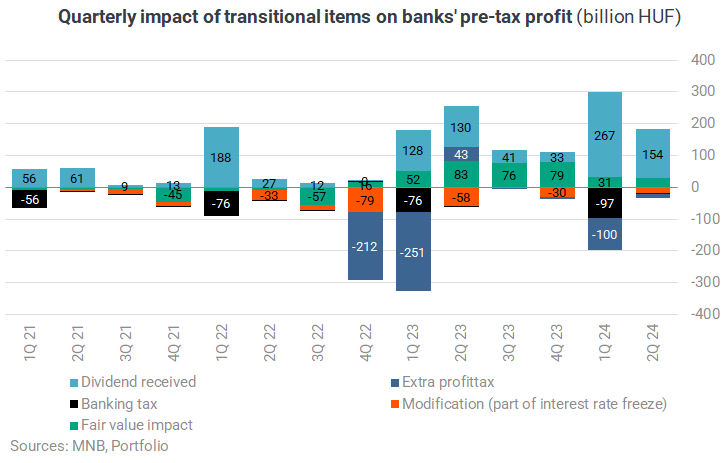
Besides commercial banks, the central bank is not in favour of this type of intervention, either. Already in its November 2022 Financial Stability Report, the MNB listed a number of factors against the measure. It said that while the interest rate cap measure significantly reduces the repayment burden of the debtors concerned, it also
- weakens the monetary transmission,
- has a negative effect on the domestic financial culture and increases the moral hazard; and
- the current form of the measure provides an unreasonably wide-ranging benefit to higher-risk, variable-rate mortgage borrowers, while
- also having several negative consequences from a macroeconomic point of view.
- There are still some 7 thousand mortgage loan contracts with over 5-year interest rate fixation periods whose interest rate changes in the eligibility period of the interest rate cap, but are not subject to the interest rate cap even after the extension.
Cover image (for illustration purposes only): Getty Images





