Retail borrowing surprises even the most seasoned bankers in Hungary


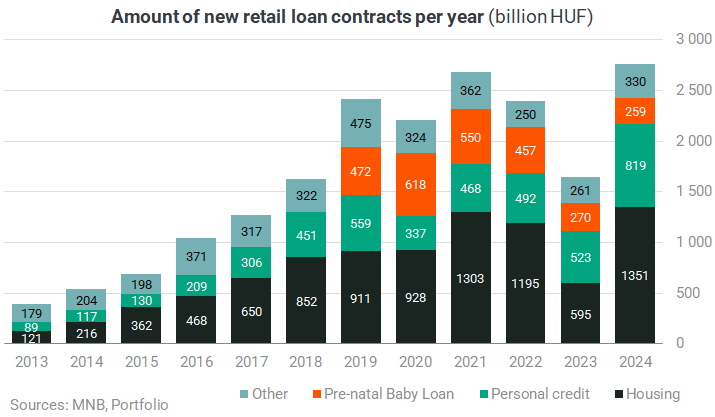
The National Bank of Hungary (MNB) published on Monday its preliminary figures on the performance of the credit market in December 2024, showing that housing loans reached a new annual high of HUF 1,351 billion, personal loans reached HUF 819 billion and household loans totalled HUF 2,759 billion.
Baby loans fell slightly due to the tightening of eligibility based on age, but this year's easing could reverse that. As for mortgages, there were big surprises compared to previous expectations: at our Lending 2024 conference in May, only 8% of the professional audience voted to beat the 2021 record of HUF 1,303 billion, and in the end the market just barely managed to do so.
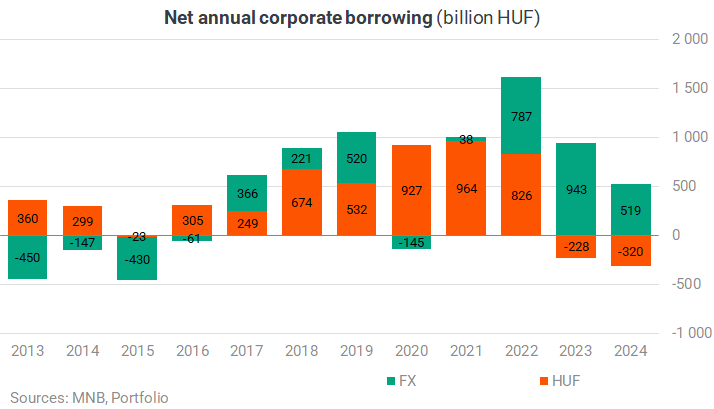
For corporate loans, it is more worthwhile to look at net borrowing (i.e. the transaction difference between borrowing and repayments): net borrowing of just HUF 200 bn is the lowest level since 2015, partly as a consequence of the near-recessionary economic environment and partly as a consequence of the abundance of corporate liquidity, which was also fuelled by previous lending programmes.
At the end of 2024, companies owed banks HUF 13 trillion in loans, while households debt amounted to HUF 11 trillion. Meanwhile, corporations held HUF 17 trillion and households HUF 13.5 trillion in bank deposits. All four stocks reached new highs.
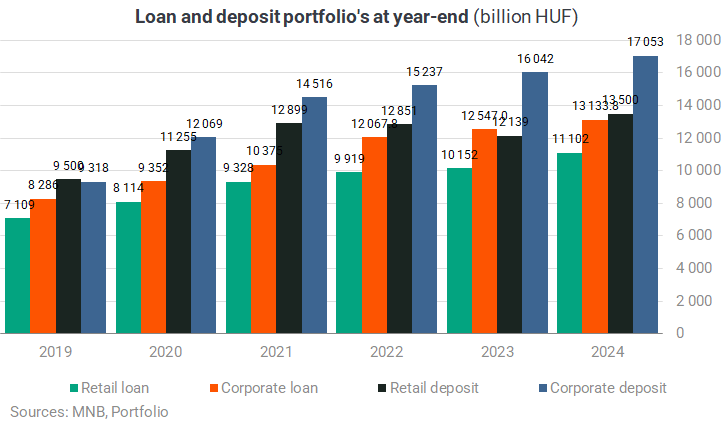
Household loans grew by 9.4% last year and corporate loans by 4.7%. However, if we adjust for the effect of the depreciation of the forint (by considering all foreign currency loans to enterprises as euro loans), the increase in corporate lending was only 1.2%, which clearly shows the split in the dynamics of the credit market. Retail deposits have returned to growth since the autumn of 2023: last year they grew by 11.2%, while corporate deposits grew by 6.3%.
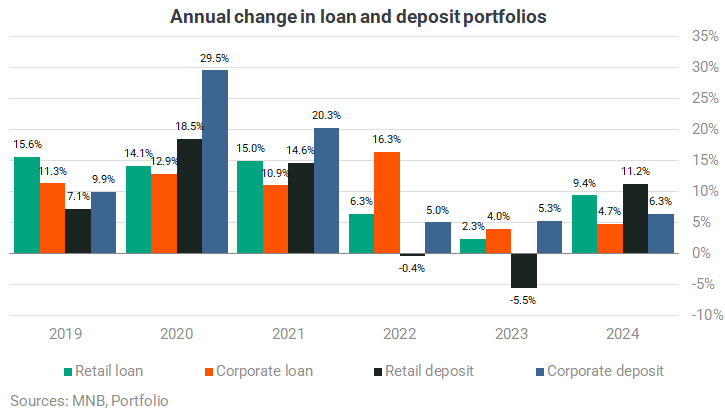
The upturn in reail lending is largely due to lower interest rates than in the previous year: on the one hand, CSOK Plus, which offers a 3% interest rate up to HUF 50 million, was launched a year ago; on the other hand, average market interest rates for housing loans fell to 6.46% by the end of 2024 from 7.35% at the end of 2023.
The bad news is that no further interest rate cuts have been on the cards for some time, except for young people moving into their first energy-efficient home, who will be able to get a loan with a maximum APR of 5% from April to October.
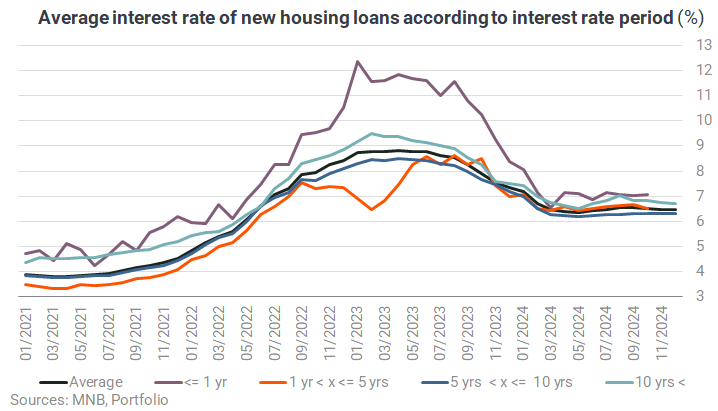
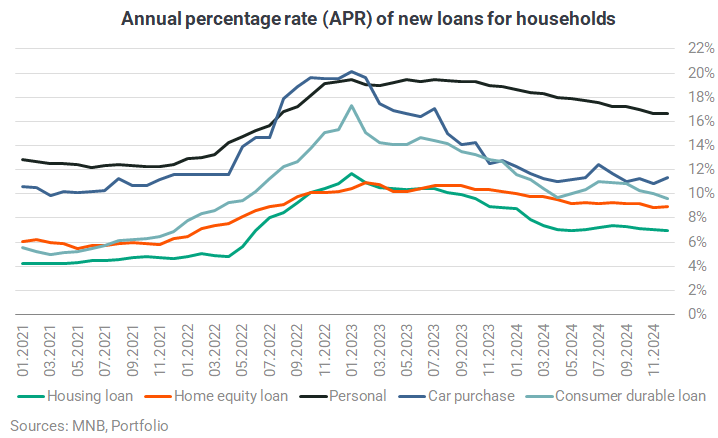
Personal loans also became cheaper last year, with interest rates falling to 16.4% in December 2024 from from 18.5% a year earlier and their APRs were 30-40 basis points higher than that. For home equity loans, which were a big hit before the 2008 crisis but are now a niche market, the average rate was around 8.9%.
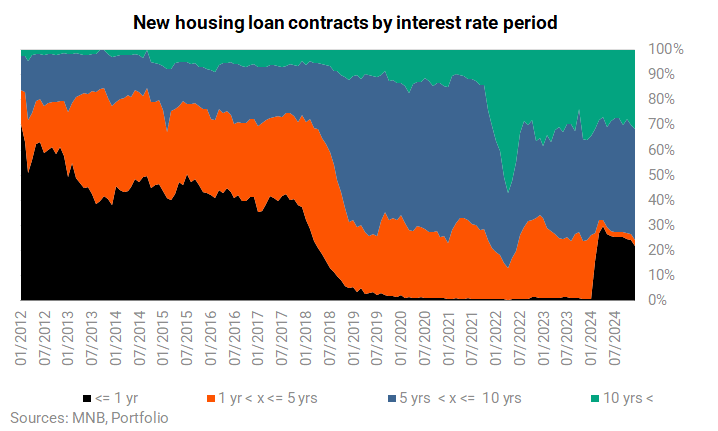
More than 95% of new housing loans last year had an interest rate period of at least 10 years, if we include CSOK Plus, which is only included in the variable-rate statistics because of its interesting interest subsidy (more exciting for banks and those that cannot comply with their commitment to have children).
As we have written on several occasions, the recovery in lending is being supported by increases in both the average amount and the number of contracts. The number of housing loan contracts rose to 75,000 from 53,000 a year earlier, while the number of personal loans rose to 305,000 from 245,000, while the number of baby loans fell to 24,000 from 27,000.
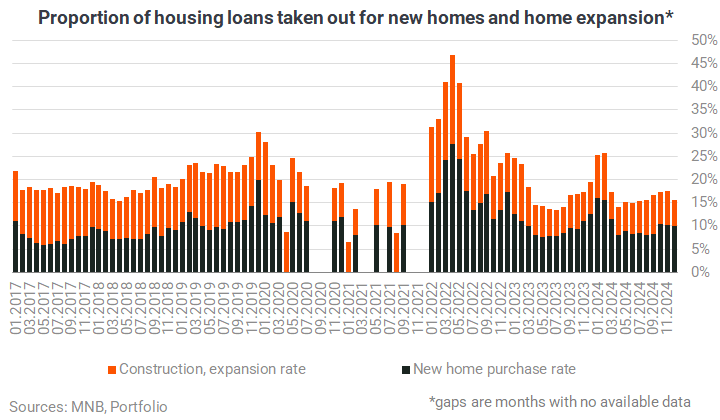
Almost 80% of housing loans were for second-hand housing, which has not yet seen the kind of breakthroughs that the MNB's Green Home Programme last saw in 2022. The extension of the 10% own contribution to green homes and some other housing policy measures could bring some change this year.
On the other hand, households did not make a breakthrough in the area of bank deposit savings last year: in December, retail savers received an average interest rate of 1.37% on their fixed/term deposits (weighted by stocks), which was even lower than the 1.77% in the previous year. For companies, the rate fell to 5.4% from 7.3%.

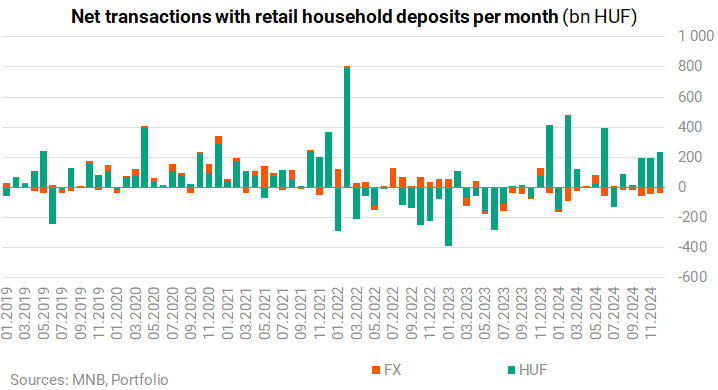
80% of retail deposits are without an agreed maturity, i.e. they don't pay even that much interest, and yet their stock has grown nicely over the past year, as we have already mentioned. In December, household bank deposits exceeded withdrawals by HUF 199 billion, and despite the weakening of the forint in recent months, the stock of foreign currency deposits on a transaction basis has been declining for five months. This is presumably to the benefit of foreign currency deposits, but more on this will soon be revealed by central bank statistics.
As in the year as a whole, the month of December was painful in terms of loans to enterprises, with net lending amounting to HUF -53 bn in the last month of the year. In 2024, companies took out HUF 318 billion less in forint loans than they repaid, while they took out HUF 511 billion more in lower-interest foreign currency loans than they repaid.
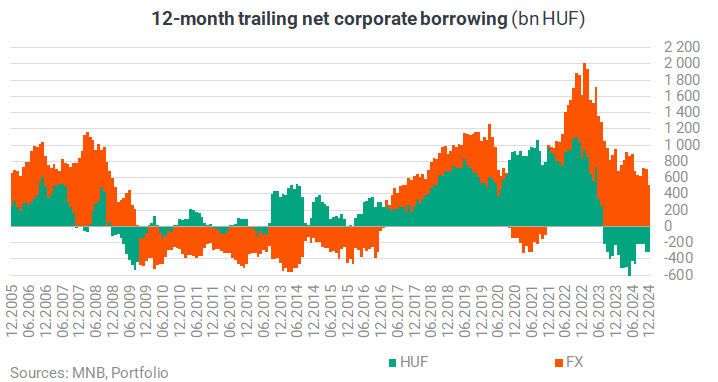
However, as we have seen above, about three quarters of the 4.7% increase in corporate lending last year was due to the revaluation effect of the weakening forint.
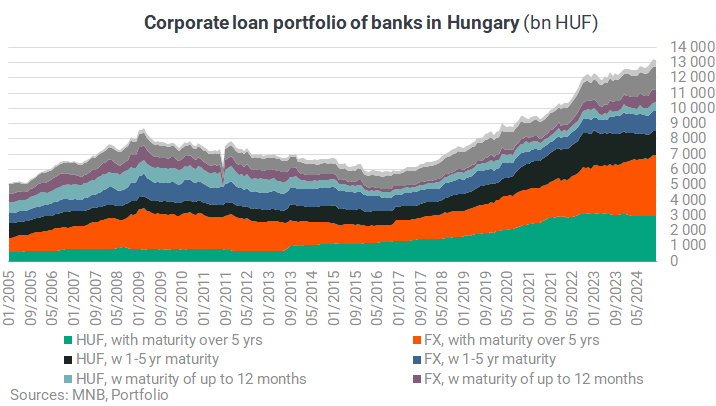
The share of foreign currency loans in the corporate loan portfolio rose to 50% from 45% last year, while the share of loans with maturity of over 12 months fell to 75% from 78%, with their stock having grown by only 0.8%, reflecting the difficulties in demand for investment loans. In this respect, the good news for SMEs is that Széchenyi Card loans for investment purposes will be available from March at an interest rate of 3%.
Cover image (for illustration purposes only): Getty Images