Hungary scraps all its plans – have credit rating agencies been scammed?


EU funds drying up
Hungary's cash deficit is expected to come in at HUF 4,774 billion this year, HUF 651 billion higher than originally planned, announced Kornél Kisgergely, state secretary in charge of public finances at the Economy Ministry, at a press conference on Tuesday. The sharp upward revision was explained by three factors:
- Funds from the European Union's Recovery and Resilience Facility (RRF) are received at a slower-than-expected pace. The cabinet expects "maybe half" of the EUR 630 bn funding planned for 2025 to be actually transferred.
- The government has amended the macroeconomic outlook, as the GDP growth assumption was slashed to 2.5% in the spring from 3.4% in the 2025 budget law.
- Meanwhile, the government has announced various new measures that will affect the budget, including a higher family tax benefit or vouchers for pensioners.
The government's argument should be treated with a pinch of salt. Well, a bit more than just a pinch to be honest.
- First of all, the estimate on receiving RRF resources of around HUF 300 billion seems rather optimistic given that Hungary is only entitled to advance payments until it has met all the super-milestones committed to in the Recovery Plan with the European Commission. None of these have been met, according to the EC's country report released on 30 May. According to the European Commission's recent country-specific report, merely 2% of the 2019-2024 country-specific recommendations (CSRs) have been fully implemented, 2% substantially implemented, and some progress has been made on 16%. This means that no progress has been made in 80% of the CSRs. According to a special analysis accompanying the European Commission's country-specific recommendations, this poor performance poses a serious risk to the drawdown and absorption of funding from the EU's 2021-2027 multiannual financial framework. In addition, the state secretary argued that the loss of recovery funds does not affect the accrual deficit because the disruption is only temporary and the funds will be received at some point in the future. However, the government's actions do not suggest that this will happen. However, the risk for the government is that the Commission will use a performance-based payment system for RRF funds. Even if the government were to complete the rule of law and transparency reforms it has undertaken as quickly as possible, payments would only be made for completed investments and projects. The deadline for these is summer 2026, so a huge rush would be needed now to ensure that the recovery money is not lost forever.
- The problem with the macro trajectory is even more significant, given that the current growth rate of 2.5% is overly optimistic and the state secretary has acknowledged that a further review is underway. Most analysts now expect annual growth of between 0.5% and 1%. However, the ministry's s reasoning is that even significant deterioration will no longer reduce tax revenues for the budget, as underinvestment and net exports are largely responsible for the worse-than-expected trajectory. However, this argument does not add up. When the government lowered its growth forecast from 3.4% to 2.5%, it expected 0.3% less tax revenue from GDP. By contrast, it would be unusual if the expected growth of 0.5–1% did not result in even lower tax revenue.
Based on this announcement, it seems that
the government is 'one step behind'.
The growth forecast has already been cut once, but until recently, the cash deficit target remained intact. However, the next — and even bigger — revision is now on the agenda. Furthermore, the RRF resources mean that the revised budget is based on highly questionable revenue projections that would be difficult to attain.
FX debt issuance must be stepped up
The change in the cash deficit target implies a similar increase in net financing needs, rising from 4.7% to 5.3% of GDP. In response, the debt manager has announced that the financing plan has been amended.
The bulk of the HUF 651 billion funding gap would be filled by foreign currency bonds, with net foreign currency issuance expected to exceed the original plan by €2.2 billion. Meanwhile, institutional issuance in forints is set to fall by HUF 344 billion to a net total of HUF 2,026 billion. However, net financing from the retail market is still expected to amount to HUF 915 billion.
This is interesting because the retail market was by far the worst performer in the first five months of the year. By the end of May, only 42% of the full year's net funding target had been met. In the institutional HUF market, meanwhile, the same ratio is 92%, and for foreign currency funding it is 127%, since the second-half-of-the-year maturities have already been pre-financed.
At first glance, it would have made more sense to curb retail issuance targets rather than those in the HUF institutional market.
Hungary could be in trouble at the rating agencies
The current changes also mean that the share of foreign currency debt will temporarily rise above the 30% benchmark. The maximum that has been in place for several years will not be raised, but the debt manager acknowledged during the presentation of the plans that the ratio could be 30.2% at the end of December, with only a minimal reduction to 30.1% in 2026.
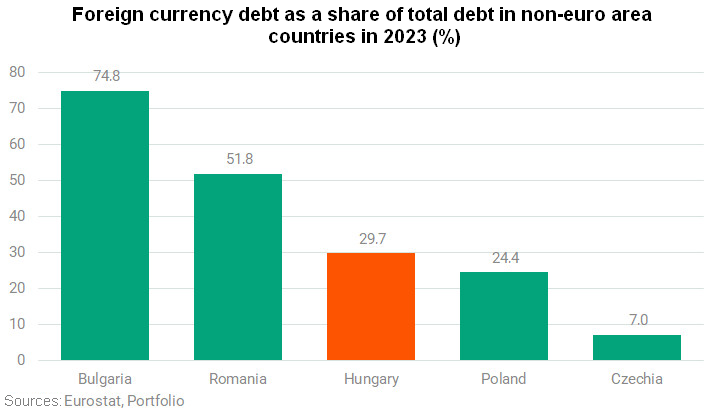
This is interesting because breaching the foreign exchange benchmark could send a negative message to the market and credit rating agencies. Currently, Bulgaria and Romania are among the EU countries outside the eurozone with the highest foreign currency debt ratios. However, from next January, the much less indebted Bulgarians will be paying in euros (they have been on a fixed exchange rate regime), so this will no longer be relevant in their case. Meanwhile, Romania has had a highly managed exchange rate in recent years. Poland, to which Hungary is more comparable, has a slightly lower foreign exchange ratio, but the Czechs have a much lower ratio and their debt ratios are much lower too.
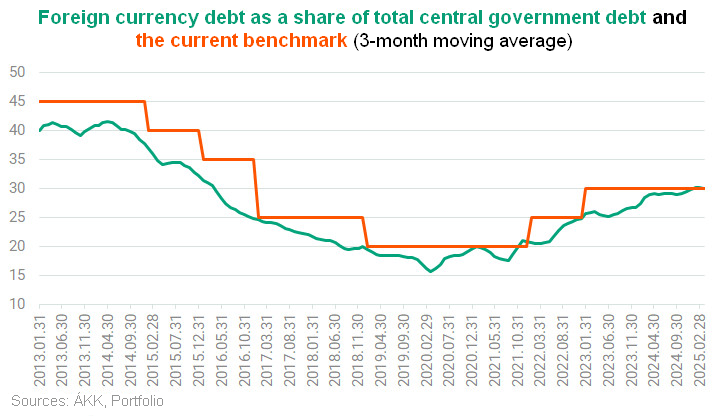
The main risk associated with a high foreign exchange ratio is the potential depreciation of the domestic currency. This would lead to a higher debt-to-GDP ratio and an increasing debt burden. This is also a key concern for credit rating agencies, who take the foreign currency debt ratio into account in their models.
A shift of a few percentage points would probably not cause an immediate negative rating move in itself, but Standard & Poor's model, for example, automatically implies a negative rating risk for foreign currency debt above 40%. Moody's model uses bands of 10 percentage points, so the current change takes Hungary from the 20–30% band to the next one up.
The timing of the announcement is also peculiar, given that both Moody's and Fitch Ratings left the Hungarian debt rating and its outlook at the same level in the past week and a half. It seems that the government has been waiting for these rating reviews before formally amending its financing plan.
Of course, it is possible that the rating agencies were briefed on these plans during the review. This is particularly likely given that the government's increased deficit target was inconsistent with the cash-flow financing plan. Ignoring this would be unprofessional on the part of the rating agencies.
However, the timing of the move is still contentious.
Of course, this 'trick' could only buy the government time until autumn at most, since all three major credit rating agencies are scheduled to review Hungary's debt rating in the second half of the year. This will enable them to assess the current decisions.
Cover image (for illustration purposes only): Getty Images





