New 3% loan hits the Hungarian market when mortgage lending is at its peak


Home Start home loan with 3% interest to be launched in a few weeks
If you have missed any of the news from the last few days, it is important to be aware of the following information:
- In announcements made on Wednesday and Thursday, the government revealed that first-time home buyers will be able to take out a subsidised home loan at 3% interest from September.
- The maximum loan amount is HUF 50 million, with a maximum term of 25 years.
- The loan requires a 10% equity contribution.
- The property price per square metre cannot exceed HUF 1.5 million, and the total property price cannot exceed HUF 100 million.
- The borrower must have had social security status for at least two years and must not own more than 50% of residential property.
- There are no restrictions on the location of the building or its energy efficiency rating, nor on the borrower's marital status or ability to have children.
The state pays the interest subsidy on the loan to the banks, enabling borrowers to pay a reduced repayment rate. According to the government, market interest rates are currently around 6.5%, meaning that a 3% home loan with a maximum term of 25 years would result in a monthly subsidy of HUF 20,000 for every HUF 10 million borrowed.

Over the maximum term of 25 years, borrowers can receive an interest rate subsidy of HUF 6 million for every HUF 10 million borrowed, meaning that with a HUF 50 million subsidised loan, they could receive up to HUF 30 million in interest subsidies based on current market rates.

Market rates are north of 6.5%
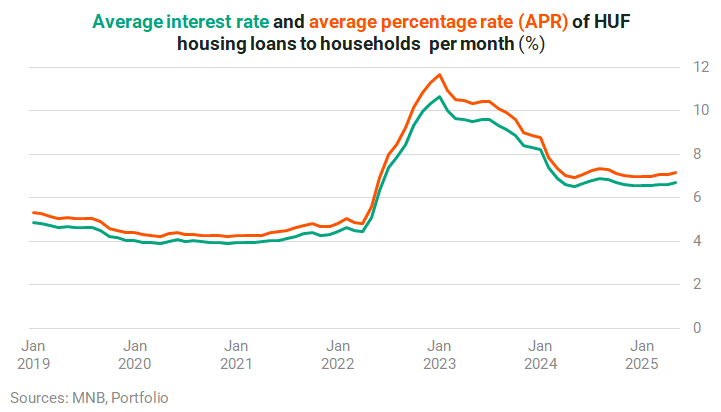
At 3%, the interest rate on the newly announced Home Start home loan is less than half the market rate. According to the latest MNB data, the contract-weighted average interest rate on housing loans taken out by households was 6.62% in April and rose slightly to 6.70% in May.
The APR, which includes all other charges, was even higher in May, reaching 7.18%,
which is a slight increase compared to 7.09% in April. It is important to note that not all borrowers face the same interest rates; those with higher incomes and requiring larger loans can usually obtain better offers than those on the market.
New record reached in the first five months
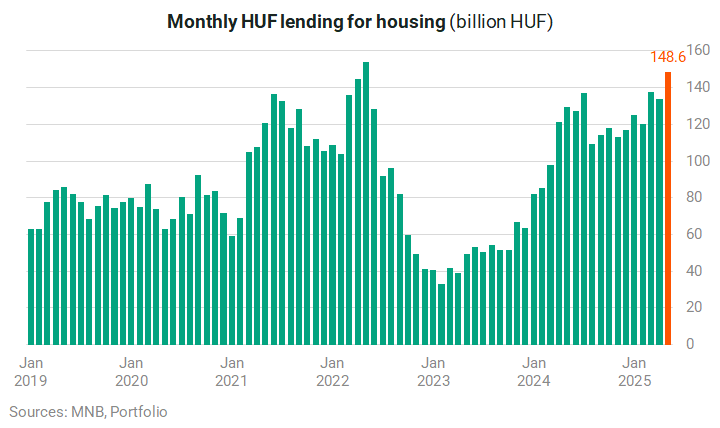
The retail credit market has already enjoyed a successful year, and the latest data from the MNB suggests that May contributed to this success. In May, HUF 148.6 billion worth of housing loans were granted in forints, of which HUF 117.9 billion were market loans and HUF 30.7 billion were subsidised housing loans. This represents a spectacular year-on-year increase of 14.7%, and a significant increase of HUF 14.5 billion compared to April.
The housing loan boom, which began in 2024 and continued strongly into 2025, is even more evident when the first five months of this year are compared with the same period last year. Between January and May this year, banks disbursed HUF 666 billion, compared to HUF 516 billion in the same period last year, representing an annual increase in housing lending of 29%.
This is a historic high for the housing loan market,
with the highest ever nominal amount of housing loans taken out by Hungarians between January and May.
A similar increase is evident in the number of housing loan contracts disbursed, with Hungarians signing 7,598 contracts in May — an increase of over 10% from the 6,889 contracts signed in April. This brings the total number of housing loans disbursed this year close to 34,000. On a year-on-year basis, the increase seen in May is slightly lower, at just over 9%, with 6,961 contracts signed in May last year.
Based on data from May, the average amount of HUF housing loans taken out exceeds HUF 19.5 million.
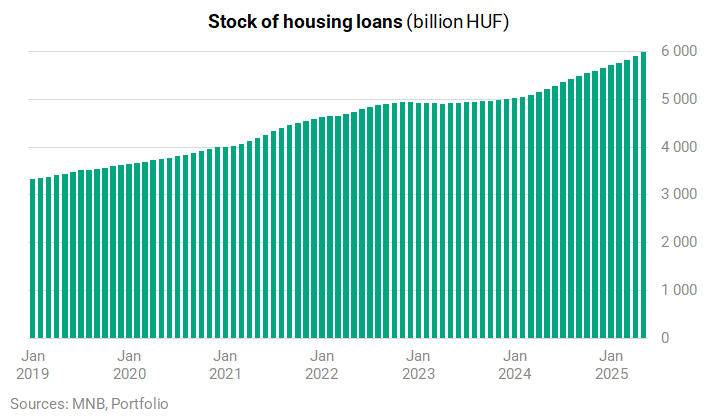
MNB publications also show that the principal outstanding on housing loans reached a new high in May, exceeding HUF 5,981 billion.
Could the 3% loan further fuel the market?
The MNB's May Housing Market Report pointed out that the subsidised CSOK Plus loan, which is available at an interest rate of 3%, is usually disbursed at a higher average amount than pure market-based housing loans.
In February 2025, the average contractual amount of market-based housing loans for the purchase of existing properties was HUF 19.8 million, which was a 27% increase on the same period the previous year (HUF 15.6 million). On a market basis, the contracted loan amount for the purchase or construction of new homes exceeded HUF 27.1 million, which was 13% higher than a year earlier (HUF 24.1 million).
The average amount of the Home Purchase Subsidy Plus (HPS Plus or CSOK Plus), which offers preferential interest rates to those planning to have children, was higher: HUF 31.0 million for a new property and HUF 25.1 million for an existing property. This is logical, given that the subsidised interest rate makes a larger loan amount available for the same income.
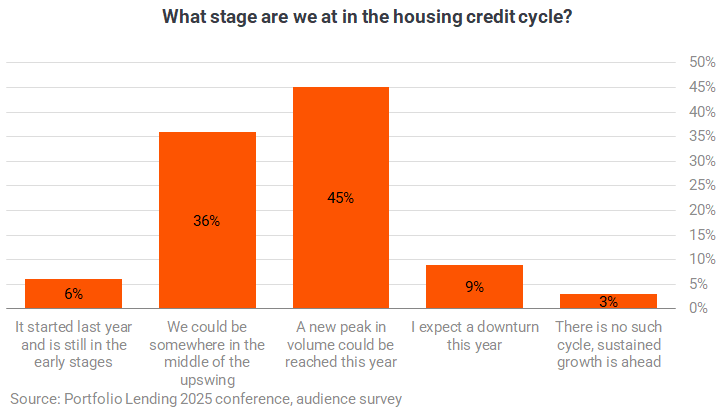
Speaking at Portfolio's Lending 2025 conference at the end of May, András Becsei, OTP's Deputy CEO, predicted that the volume of new lending could reach HUF 1,600 billion this year.
At the same time, there are strongly diverging views within the banking industry on the state of the housing loan cycle. The majority (54%) said that the recovery from the lending trough of 2023 could end this year. The most popular view (45%) was that new lending volumes could peak this year and fall next year, while a further 9% said that lending could fall as early as 2025.
The introduction of the 3% home loan, even if it is only available for the last four months of the year as the government plans, will change the situation fundamentally. For those who qualify, access to the 3% loan with unchanged repayments could increase demand for credit by up to 42%.
For example, if you could afford to repay a HUF 30 million home loan at market interest rates, the Home Start Programme could give you access to a HUF 43 million home loan with the same monthly commitment.
Another important factor is that the equity required for the Home Start Programme is lower than the 20% minimum required for market loans. The 10% equity requirement
enables prospective buyers who have previously been unable to purchase their first home due to insufficient equity to enter the market.
This would, in turn, generate new demand in both the credit and property markets.
How much this scheme will burden state coffers?
At a press conference last Thursday, Gergely Gulyás, the PM's chief of staff, predicted that the Home Start Programme would not have a significant budgetary impact this year, given that the most likely scenario is that the government and the banks will settle the interest rate subsidy in 12 months.
Depending on the number of applicants, the minister estimates that the interest rate subsidy could cost the budget between HUF 50 billion and HUF 150 billion per year from 2027 to 2029. The range is so wide because it is not known how many borrowers will take advantage of the opportunity.
Gulyás also said that, for a HUF 50 million loan, an interest subsidy of between HUF 15 and 25 million can be expected over the 25-year term. Based on current interest rates, the subsidy would be closer to HUF 25 million. However, it is realistic to expect that market interest rates will fall in the future, meaning that a subsidy of HUF 15 million could become the norm in the long term.
The two statements also provide an indication of the number of borrowers that the government anticipates. Assuming a maximum interest subsidy of HUF 1 million per borrower per year under current market conditions (based on the indicated figure of HUF 25 million) and expecting a budgetary impact of at least HUF 50 billion in 2027, at least 50,000 loans could be taken out in 2025 and 2026.
Cover image (for illustration purposes only): Getty Images





