Hungarian gov't decides on tax cut but this will definitely have consequences

Much-awaited proposal lands
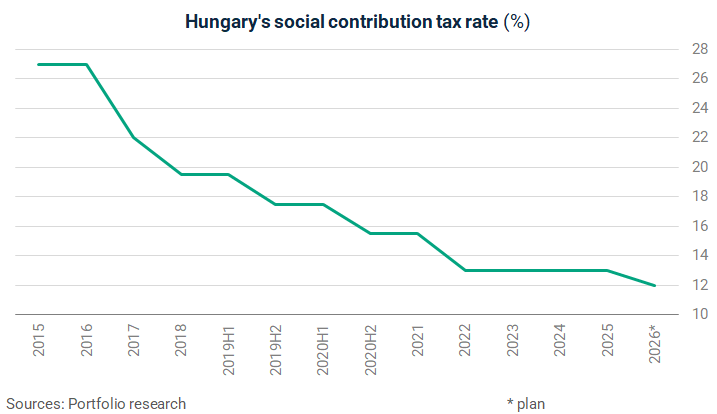
It was quickly decided that the social security contribution rate of 13%, which had been in effect since January 2022, would be reduced to 12%. On Monday morning, it emerged that the government was contemplating tax cuts to support Hungarian businesses. Subsequently, proposals from businesses were submitted, and a 1 percentage point reduction in the social contribution tax rate was discussed at a meeting involving the Economy Ministry and the Permanent Consultation Forum between the Competitive Sector and the Government (VKF). By Tuesday, it was clear that a further reduction in the tax burden had been agreed.
Based on all this, it is clear that the government is gradually revealing its latest economic policy measures, which will impact the state of the budget to a greater or lesser extent. This approach allows it to achieve several objectives at once:
- Firstly, it can communicate measures supporting individual economic actors at length and on an almost daily basis, as — amidst fierce political competition ahead of the 2026 parliamentary elections— it is increasingly important for the government to emphasise steps aimed at improving its popularity.
- Secondly, gradually feeding new information into the market makes it easier for market participants, debt financiers and credit rating agencies to accept that the government has not only jumped on the fiscal easing bandwagon, but has been riding it for quite some time.
Why this?
In recent months, the government has announced a number of measures aimed at helping specific groups in society. These include providing pensioners with vouchers, launching the preferential 3% Home Start loan programme for first-time homebuyers, doubling family tax allowances and extending income tax exemptions for mothers.
Tax relief measures aimed at improving operating conditions for businesses are now on the table. Social security contributions are usually paid by employers, and the state uses this revenue to finance social security initiatives. This type of tax increases the income of the Pension Insurance Fund and the Health Insurance Fund.
The question arises as to why the government has resorted to the social contribution tax this time. Anyone who has been reading Portfolio's articles in recent months will not be entirely surprised by this measure. We had already predicted that the government was preparing further fiscal easing measures, and we recently forecasted specifically that social security contributions could be one such area. Therefore, a further reduction in the social contribution tax rate is linked to the sustainability of the current wage agreement.
It is worth remembering that, in November 2024, employees and employers signed a three-year wage agreement. Under this agreement, the minimum wage increased by 9% this year, with further increases of 13% and 14% scheduled for 2026 and 2027 respectively. However, the domestic economic environment, which determines the operating conditions of domestic companies, has changed radically in the meantime.
In recent months, the corporate sector has issued warnings that the planned wage increase is not sustainable if we accept that domestic wages can only be raised in proportion to the performance of the Hungarian economy and productivity improvements.
In essence, the government paid heed to the warnings and
decided to add a spoonful of sugar to the bitter pill of substantial wage increases it is shoving down companies' throats.
This is the purpose of reducing the social contribution tax rate, which provides relief mainly to those sectors where employment at the minimum wage is prevalent. This is because companies operating in these sectors would have to manage a mandatory 13% minimum wage increase next year, but certain segments of these sectors face the most challenging operating conditions.
At the time of the three-year wage agreement, the government anticipated a significant increase from this business segment, so it was agreed that those on the minimum wage would only have to pay the increased social contribution tax on a 'sliding scale'. This meant that in 2025, they would pay the 2024 rate; in 2026, the 2025 rate; and in 2027, the 2026 rate.
The practice of reducing social contribution tax is nothing new. Consider, for example, the six-year wage agreement concluded in 2016, under which the government compensated companies for the burden of higher wages by reducing social contribution tax in several stages, subject to certain conditions. The aim was to reduce companies' tax burden, and this is essentially continuing now.
We presented the split in tourism in our recently published analysis:
Fits into the series of fiscal easing measures
Another interesting question is how the government will be able to finance the increasing number of fiscal easing measures. The answer is quite simple: the Economic Development Framework. We have written about how this works and its background in this article. The bottom line is that the government will have HUF 800-900 billion at its disposal next year, which it can spend freely on economic development and stimulus measures.
Let's not forget the government's goal, as regularly stated by the Economy Ministry, which is responsible for the economy and the budget:
The goal remains unchanged: we are working to ensure that economic growth is as high as possible.
The cabinet regularly succumbs to the temptation to spend from the Economic Development Framework:
The Home Start preferential loan programme could result in an additional interest expenditure of HUF 50-70 billion next year.
The government has allocated HUF 16 billion of this amount to increase the number of state-funded ultrasound examinations.
In early July, the government withdrew over HUF 7 billion for road investments.
A recent government decision is to transfer HUF 42 billion from the budget to continue raising government officials' salaries.
This could be exacerbated by the effect of the social contribution tax reduction, which Márton Nagy says could result in a loss of HUF 200 billion in revenue.
In other words, the government has already allocated more than HUF 330 billion from this new budget reserve, proving that it has become rather spendthrift.
We can see that there is no problem with the state's liquid reserves, as the amount of cash readily available in the Treasury Single Account (KESZ) has reached an all-time high.
Time bombs planted
As mentioned above, since this payment obligation typically falls on employers based on their employees' income, the 1 percentage point reduction also serves to compensate for expected forced wage increases. Employers have emphasised in several forums that the Hungarian tax burden is high, and the government is now conceding on this point.
However, it should also be noted that the government is deliberately placing additional burdens on certain sectors through measures such as special taxes and extra profit taxes. Therefore, this type of social contribution tax reduction represents barely noticeable relief for certain sectors when considering companies' total tax burden in that sector.
Since these are alternative economic paths that did not actually occur, we will never know what would have happened in an economic environment where the government did not rely so heavily on anti-market measures, such as special taxation, which distort competition and are often selective. The government refers to these measures as 'greater burden-bearing capacity' of the targeted sectors. It is possible that the Hungarian economy would flourish more on these alternative paths, as the sectors that drive economic growth would operate in a more supportive environment.
We have written the following analysis on this issue:
We just want to highlight that there are significant factors at play in the Hungarian tax system, and that economic policy measures such as those currently being implemented only serve to reinforce this.
The reduction in social contribution tax shifts the tax revenue structure further towards consumption-based revenues. While it does not turn the entire revenue side of public finances upside down — especially given that VAT revenues are flowing nicely into the state coffers, employment is stable and the related taxes are also generating revenue, and the HUF 200 billion loss stemming from the cut to the social contribution tax can be recouped through higher wages and the associated personal income tax, as well as through higher VAT revenues due to a possible increase in consumption — it does further increase the dependence of social security funds.
Contributions and social security revenues make up a large part of the income of the Health Insurance Fund and the Pension Insurance Fund. Reducing this type of tax causes a major shortfall in these areas, further reinforcing the idea that these systems are becoming increasingly unstable.
This, in turn, has an impact on the entire state budget. If these funds generate a deficit — and there are no fewer pension- and healthcare-related government promises, but rather more promises and potential expenditure on the horizon — then these funds will have to be supplemented with increasingly large amounts from the central budget.
In other words, the government has created a time bomb in the financing of its own social security systems by gradually reducing social contribution tax in recent years.
András Farkas, a pension expert and the founder of NyugdíjGuru News, as well as a regular external contributor to Portfolio, recently wrote an article about the impact of these measures on pension funds.
One interesting aspect of such a tax reduction is how companies might respond to it. Hypothetically, they have three possible courses of action:
-
They pass on the full effect of the reduction in social contribution tax to their employees, meaning the latter group's disposable income increases.
-
Companies absorb the benefits of the reduction, which is reflected in their profits.
- They implement a combination of the above two options.
As reactions may vary from sector to sector and company to company, it will be interesting to see what the macro figures show in 2026.
Let's not forget this either!
Since 1 July 2023, most interest income has been subject to a 13% social contribution tax, with a few exceptions (e.g. interest on retail government securities). Therefore, if the general social contribution tax reduction is implemented, interest income will also incur a lower tax burden.
Cover photo: MTI Photo/Vivien Cher Benko





