If this scenario materialises, Hungary will be in serious trouble and will need massive funding


Serious problems in the Hungarian budget
According to IMF staff, the Hungarian budget will face serious challenges in the coming years. There will be little meaningful deficit reduction after the 4.7% of GDP deficit in 2025, and the gap could still be 4.3% in 2030. While this year's and next year's forecasts align with market expectations,
it is surprising that the IMF anticipates no significant fiscal adjustment in the medium term.
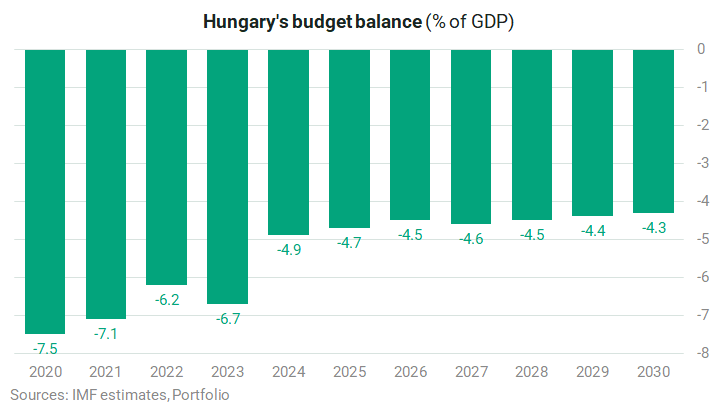
IMF notes that a further deficit reduction to below 2% by 2028 is envisaged in their medium-term fiscal structural plan (MTFSP). However, neither the budget nor MTFSP identifies sufficient savings measures to achieve the fiscal targets. As shown in table below, savings from recently renewed windfall taxes and other measures are more than offset by costs from tax policy initiatives and higher spending on housing and SMEs.

Hungary's Medium-Term Fiscal Structural Plan
In the context of the EU’s Economic Governance Framework, Hungary adopted its 2025-28 Medium-Term Fiscal Structural Plan (MTFSP) in January 2025. The plan targeted ex-ante (i) a reduction in the fiscal deficit below 3% of GDP by 2026, (ii) 0.5% annual consolidation in the structural primary balance, and (iii) a minimum annual decline in the debt-to-GDP ratio of 0.5%.
The plan is operationalized through expenditure ceilings. The annual nominal growth of net expenditure is capped at a 4% on average over the four-year adjustment period. While the MTFSP is based on an average 2% annual real GDP growth, deviations from those assumptions could result in higher ex-post deficits and debt even under compliance with the expenditure target. The net expenditure rules also provide room for deviation from the target up to 0.3% of GDP annually or 0.6% cumulatively.
The newly introduced defense escape clause provides extra flexibility by allowing countries to raise defense expenditures relative to the 2021 level by up to 1.5% of GDP above the expenditure target. Hungary had already increased defense expenditures by 0.9% of GDP between 2021 and 2025 and can deduct this amount to meet its expenditure target.
As a result, Hungary could remain compliant with the net expenditure rule even under a higher deficit and debt path than initially planned, weakening its role as a fiscal anchor.
The IMF recommends that the Hungarian government come up with a credible and sustainable package as it would be "essential to rebuild fiscal buffers" in order to create maneouvring room in case of a global shock. This, however, will not happen on its own. Further steps are required, e.g. to make state subisides and preferential loans more targeted.
A buffer-stock model calibration that reflects policy trade-offs between supporting output and medium-term debt sustainability suggests an optimal structural promary balance (SPB) surplus of 1.75% of GDP in the medium term and an implied cumulative adjustment of about 2% of GDP between 2025-28. For 2025, the focus should be on meeting the budget target, which staff estimates would require additional measures of 0.5% of GDP relative to its baseline. Staff proposes a further cumulative adjustment of 1.3% of GDP in 2026 and 2027 to bring the headline deficit below 3% in 2027. Any additional defence spending should be accommodated within staff’s recommended adjustment path.
If we look at the IMF's detailed analysis, we can see what the above budgetary trajectory is based on: they expect budget interest expenditure to remain persistently high.
By contrast, the Hungarian government is basing its fiscal policy on the assumption that interest expenditure will gradually decline after peaking in 2024–25. This will allow the deficit to fall while maintaining a near-balance primary surplus. As the figure below shows, with debt ratios already high in the region, it is likely that Hungary's interest expenditure will remain the highest for a long time to come.

It is clear that Hungary stands out from the rest. This can only partially be explained by its higher debt ratio, as experts estimate that Slovak and Romanian public debt will rise to similar levels relative to GDP by 2030, yet financing will be cheaper.
According to IMF estimates, Hungary's nominal budget interest expenditure could exceed HUF 5,000 billion by 2030 and remain at 4–5% of GDP over the next five years. This is largely why,
even if the primary balance of the budget is in equilibrium, the deficit may remain high due to interest rates.
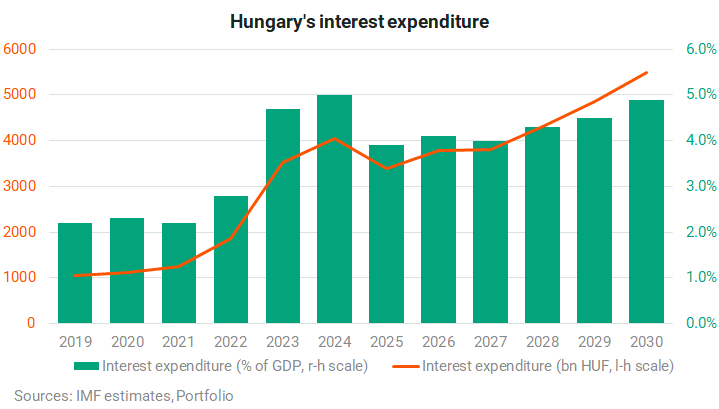
There is no detailed explanation of the basis on which the IMF makes its forecast of high interest rate expenditure. The prevailing view in domestic public discourse is that following the inflation-linked retail government bond interest rate shock in 2023–24, interest payments could significantly and permanently decrease. However, the situation is more complex than that.
- Hungary already has the highest debt ratio in the region, meaning a larger proportion of maturing debt must be refinanced each year.
- Forint bonds issued at low interest rates in the past will mature in the coming years and can now be renewed at significantly higher yields. Here's just one example: According to IMF data, the yield on Hungary's 5-year benchmark averaged 2.4% in 2021. This could rise to 6.6% this year and gradually increase to 7.3% by 2030. In other words, the era of cheap money is not expected to return in the medium term, which will put pressure on the Hungarian budget due to higher yields.
According to IMF experts, Hungary will continue to finance most of its budget by issuing medium- and long-term government securities in forints, while inflation-linked retail securities could play an important role in its debt management strategy. Meanwhile, the government intends to maintain the foreign currency debt ratio at approximately 30%.


How will this lead to debt reduction? It won't.
The persistently high budget deficit may also affect the trajectory of public debt relative to GDP. According to recent analysis, public debt may rise from 73.5% in 2024 to 78.6% in 2030, with
the IMF forecasting that there will not be a single year in which it declines.

The public debt ratio will increase over the medium-term reflecting unfavorable debt dynamics and only modest fiscal consolidation, the IMF projects. GFNs are expected to jump to 22% of GDP in 2025 given higher than anticipated redemptions of retail bonds and issuance of short-term debt, and to remain elevated, averaging around 17% through 2030.
The inflation-linked portion of public debt is a risk factor that could add to servicing costs if inflation rises or to financing needs if redemptions increase.
The debt ratio will increase through the medium-term and remain well above the EU target of 60% and above Hungary's own 50% target through the entire projection period, the Fund projects.
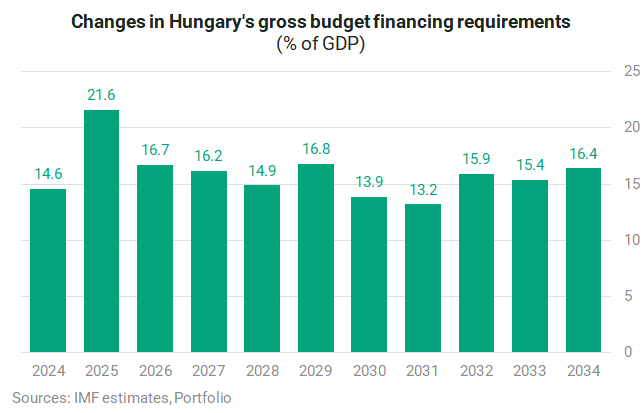
Overall, the IMF acknowledges that
the risks to the sustainability of Hungary's debt are moderate. However, it adds that these risks have increased over the past year and a half,
since the last comprehensive analysis was conducted.
Banks’ sovereign and FX exposures
Following tighter conditions for claiming windfall tax credits in 2024, banks’ holdings of government securities rose.
As a result, Hungary now ranks highly among CESEE peers in terms of banks’ sovereign exposures, which amplifies macrofinancial risks under the sovereign-bank nexus,
the IMF warned.
While banks are meeting FX-related regulatory ratios, there has been a significant rise in their aggregate short FX positions.

This is problematic because, if the government fails to reduce the deficit and create room for manoeuvre with further measures, there will be nowhere to turn in the event of a global shock. This is because it cannot be relied upon that the banking sector will be able to absorb significant additional amounts of government securities if necessary.
Cover image (for illustration purposes only): Getty Images





