Equity
What kind of bank could Hungary's OTP buy next?

Not a new story
The sell-off of Serbia’s Komercijalna Banka has been dragging out for a while now. Serbian newspapers learned back in 2017 that the privatisation of the bank was starting, but the sell-off never took place, and the cabinet has just published the privatisation announcement in daily Politika only now.They mentioned OTP among the Serbian bank’s potential buyers already two years ago, and it is still considered as one. The situation is totally different at present than in 2017, though. Since then OTP has acquired Vojvodjanska and SocGen’s Serbian unit, and by integrating its new assets it will become the second-largest financial institution in the country, behind Intesa and taking over UniCredit.
Komercijalna is a large bank in Serbia
Komercijalna is the fourth-largest bank in Serbia, behind Intesa, OTP’s local operation (OTP+Vojvodjanska+Socgen) and UniCredit, with total assets of 390 billion Serbian dinar at the end of September 2018 (nearly HUF 1,040 bn at the current exchange rate). For the sake of comparison, total assets data for Serbian banks are for end-Sept 2018, while Komercijalna’s total assets stood at RSD 403 billion at the end of March this year (cc. HUF 1,080 bn).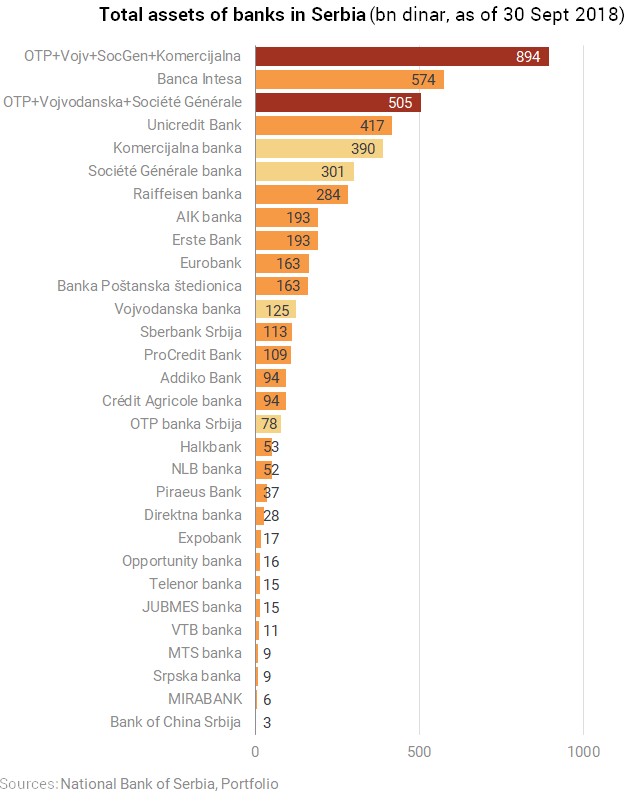
What is there to know about this particular Serbian bank?
In 2018, Komercijalna served its customers in 202 branches, with 271 ATMs and 13,600 POS terminals.
Source: Komercijalna
The Serbian bank is a retail-focused financial institution. More than 55% of its total loans were extended for households and over 80% of its deposits were held by retail customers. Komercijalna closed 2015 and 2016 in the red, but last year it reached a return on equity (ROE) of about 12%. In the last two years, its annual after-tax profit was RSD 8.1 bn (cc. HUF 22 bn). The medium-term outlook of the management is the following : total assets up by 4.5-5.8%; ROA around 1.9%; ROE around 11%; cost/income ratio down at 55.3% from last year’s 58%; NPL ratio to decline to 6.8% from 9.5% in 2018.Why should OTP buy Komercijalna?
- OTP is active in the region in the last few years it bought 11 banks here, and although its management said after the most recent acquisition in Slovenia that OTP will take a rest for a while, they remain open to lucrative businesses, and after the integration of the new assets they plan to have another acquisition round.
- OTP primarily buys banks on markets it has already entered, and Serbia is one of those countries.
- OTP is vastly experienced in acquisitions, and conducting a new takover would not be a problem for it.
- OTP is sitting on a mountain of excess liquidity, it has way more than enough funds to buy Komercijalna.
Why should OTP not buy Komercijalna Banka?
- OTP has recently made it clear that after a series of acquisitions over the last few years it will hang up its gloves for a while, and focus on the integration of its new assets (while, of course, keeping its eyes peeled for good bargains - see the arguments in favour of this deal above).
- OTP will become one of the largest banks in Serbia after taking over Vojvodjanska and SocGen’s local operation. The question is what the Serbian central bank/financial authority/competition authority will have to say about the Hungarian bank becoming the country’s way largest bank by a new takeover.
- With its existing Serbian assets OTP already has an optimal economy of scale in the country for profitable operation, and becoming the largest bank in Serbia does not seem to be an unreachable goal even via organic growth.
- The integration of the new Serbian assets is a large enough task in itself. This might not be the best time to buy another bank and start to integrate it too.





